Canada Pension Plan Enhancement: Boost Your Retirement by 15%
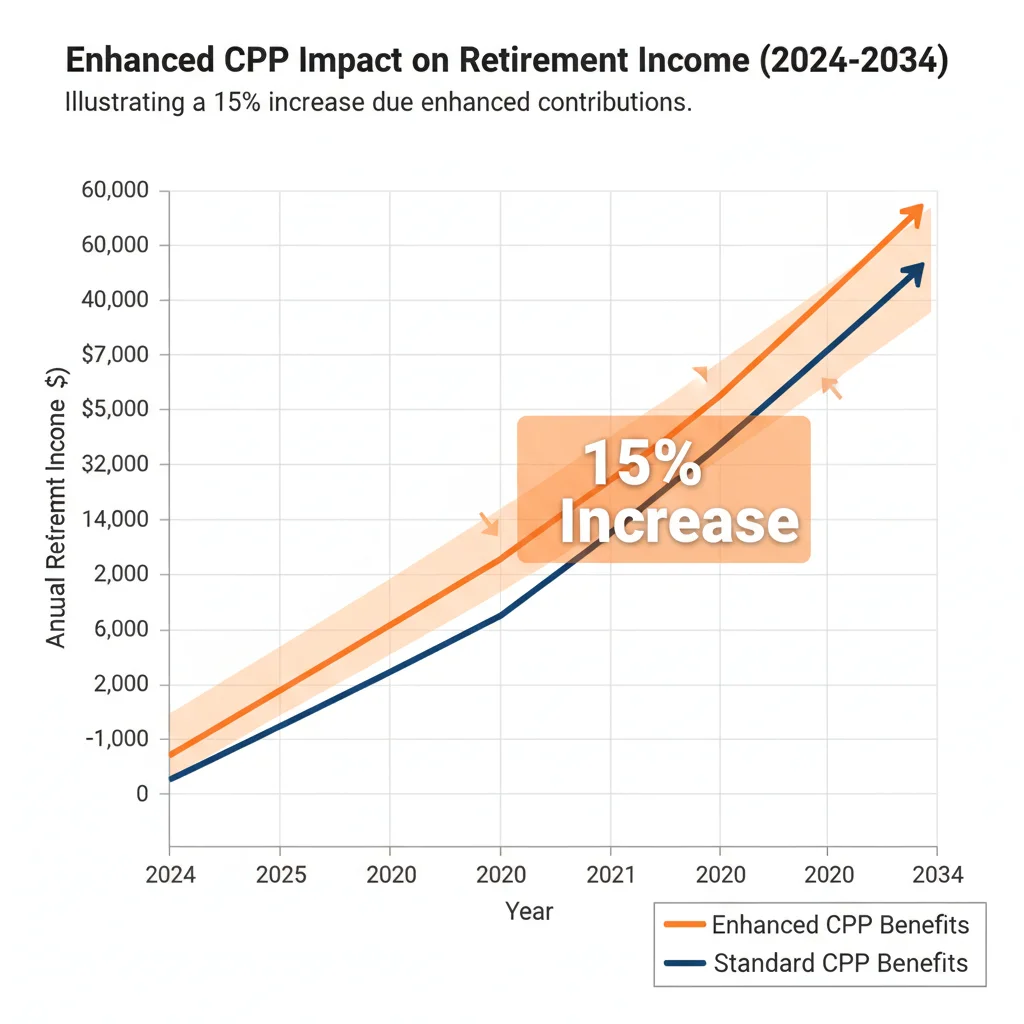
The Canada Pension Plan Enhancement is a significant change affecting retirement income for Canadians. This article breaks down how these enhancements work, who is impacted, and what you can expect your retirement benefits to look like over the coming decade, potentially increasing by 15%.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
The Canada Pension Plan (CPP) is a cornerstone of retirement security for millions of Canadians. It provides a steady stream of income in retirement, helping to cover essential living expenses. In recent years, significant changes have been made to the CPP, known as the Canada Pension Plan Enhancement. These enhancements are designed to provide greater financial support for future retirees, with projections indicating a potential boost of up to 15% in retirement income over the next decade for those who contribute more under the new rules. Understanding these changes is crucial for anyone planning their financial future and hoping for a comfortable retirement.
This article will explore what the Canada Pension Plan Enhancement entails, how it works, and what it means for your personal retirement planning. We’ll break down the increased contributions, the expanded benefits, and the timeline for these changes to fully take effect. By the end, you’ll have a clearer picture of how these enhancements can positively impact your financial well-being during your golden years, ensuring you are better prepared for what lies ahead.
Understanding the Canada Pension Plan Enhancement
The Canada Pension Plan Enhancement represents a significant evolution in Canada’s retirement income system. Historically, the CPP aimed to replace about one-quarter of a person’s average work earnings up to a certain maximum. However, with the rising cost of living and changing economic landscapes, there was a recognized need to strengthen this foundational pillar of retirement support. The enhancements, which began in 2019, are a direct response to this need, aiming to increase the amount of income Canadians receive in retirement from the CPP.
The core idea behind the enhancement is simple: if you contribute more during your working years, you’ll receive more in retirement. This involves a gradual increase in both contribution rates and the earnings ceiling over several years. The goal is to boost the maximum CPP retirement benefit by about 50% for those who contribute for 40 years under the enhanced plan. This translates to a substantial increase in financial security, especially for younger generations who will contribute for a longer period under the new rules. It’s a proactive measure to ensure the CPP remains relevant and robust for future retirees.
The enhancement doesn’t just impact retirement benefits; it also extends to other CPP benefits, such as disability benefits and survivor benefits. This holistic approach ensures that a broader range of Canadians and their families receive increased support when they need it most. The phased implementation allows individuals and businesses to adjust to the new contribution rates over time, making the transition smoother. Ultimately, the Canada Pension Plan Enhancement is about improving the quality of life for Canadians in their retirement years, providing a more substantial safety net against financial uncertainties.
How Increased Contributions Drive Higher Benefits
The fundamental principle behind the Canada Pension Plan Enhancement is a direct link between increased contributions and higher future benefits. For years, both employees and employers contributed a set percentage of earnings to the CPP, up to a maximum amount. The enhancement introduces a gradual increase in these contribution rates, along with the creation of a second, higher earnings ceiling. This means that over time, a larger portion of a worker’s earnings will be subject to CPP contributions, leading to a more robust pension payout in retirement.
Starting in 2019, the first phase of the enhancement involved a steady increase in the contribution rate on earnings up to the original maximum annual pensionable earnings (YMPE). This phase continued until 2023. The second phase, which began in 2024, introduces the additional CPP contribution (ACC) and a new, higher earnings ceiling called the Year’s Additional Maximum Pensionable Earnings (YAMPE). This means that once your earnings exceed the YMPE, you’ll start contributing a different, lower percentage on earnings up to the YAMPE. These additional contributions are what fund the enhanced portion of your future CPP benefits.
Understanding the Two Tiers of Contributions
First Additional Contribution Rate: This applies to earnings between the existing Year’s Basic Exemption (YBE) and the Year’s Maximum Pensionable Earnings (YMPE). Both employees and employers contribute a slightly higher percentage in this tier, which gradually increased from 2019 to 2023.
Second Additional Contribution Rate: Starting in 2024, this new rate applies to earnings between the YMPE and the new YAMPE. This tier ensures that higher earners contribute more to the enhanced portion of the CPP, further strengthening their future benefits.
Employer and Employee Shares: Both employers and employees typically share the cost of CPP contributions equally. Self-employed individuals pay both the employer and employee portions.
It is important to remember that these increased contributions are not just deductions from your paycheck; they are investments in your future financial security. The more you contribute under the enhanced plan, the greater your potential retirement income from the CPP will be. These changes are designed to provide a more substantial and reliable pension, particularly for those who will contribute for many years under the enhanced rules.
The Timeline and Phased Implementation
The Canada Pension Plan Enhancement is not a sudden overhaul but rather a carefully planned, multi-year implementation designed to allow individuals and employers to adapt. This phased approach ensures stability and predictability within the system. The journey began in 2019 and will continue to unfold over the next decade, with different stages introducing new contribution rates and benefit calculations. Understanding this timeline is key to grasping how and when the enhancements will fully impact your retirement.
The initial phase, from 2019 to 2023, focused on gradually increasing the CPP contribution rate on earnings up to the first earnings ceiling (YMPE). During these five years, the contribution rate slowly climbed, meaning both employees and employers were contributing slightly more each year. This period laid the groundwork for the more significant changes that followed. The idea was to incrementally build up the fund that would support the enhanced benefits, without imposing an immediate, large increase on contributors.
The second major phase commenced in 2024, marking the introduction of the second earnings ceiling, known as the Year’s Additional Maximum Pensionable Earnings (YAMPE). This new ceiling is set at a higher level than the YMPE. For earnings between the YMPE and the YAMPE, a new, lower contribution rate applies. This structure ensures that a greater portion of higher earners’ incomes contributes to the CPP, further bolstering their future benefits. This dual-tier contribution system is a cornerstone of the enhancement, allowing for a more progressive and robust funding model.
The full impact of these enhancements on retirement benefits will gradually become apparent over the coming decades. Individuals who contribute for 40 years under the enhanced CPP will see the most significant increase in their retirement income. This means younger workers entering the workforce now will benefit the most, as they will have the longest period to contribute under the new, higher rates. For those closer to retirement, the impact will be less dramatic, but still positive, depending on how many years they contribute under the enhanced rules. The 15% increase in retirement income over the next decade refers to the projected growth for those who consistently contribute under the new system.
Who Benefits Most from the Enhancement?
While the Canada Pension Plan Enhancement is designed to improve retirement security for all Canadians who contribute, certain groups stand to benefit more significantly than others. Understanding these dynamics can help individuals assess their own potential gains from the enhanced plan. Generally, those with longer working careers under the new contribution rules and those with higher earnings will see the most substantial increases in their future CPP retirement income.
The primary beneficiaries are younger workers and those still early in their careers. Since the enhancements began in 2019 and involve a gradual increase in contributions over many years, individuals who will contribute for a full 40 years under the enhanced system will experience the maximum benefit. For these individuals, the CPP is projected to replace a larger portion of their pre-retirement earnings, moving from approximately one-quarter to one-third. This translates into a much more comfortable and secure financial foundation during retirement, potentially boosting their CPP income by a significant percentage compared to the old plan.
Another group that will see considerable benefits are those with earnings above the first earnings ceiling (YMPE). With the introduction of the second earnings ceiling (YAMPE) in 2024, individuals earning more will contribute on a larger portion of their income. These additional contributions directly translate into higher benefits from the enhanced portion of the CPP. This means that while everyone contributing will see some benefit, higher earners will see a more pronounced increase in their overall CPP payout, as their contributions are spread across a wider range of income.
It’s also worth noting that the enhancement benefits not just retirement pensions, but also other CPP benefits. This includes disability benefits, survivor benefits, and post-retirement benefits. This means that if a contributing worker becomes disabled or passes away, their family members may also receive higher benefits under the enhanced plan. This broader scope of increased support adds another layer of financial protection for Canadian families, making the CPP even more comprehensive in its social safety net. The overall aim is to ensure a more robust and responsive pension system for the diverse needs of Canadians.
Planning Your Retirement with the Enhanced CPP
The Canada Pension Plan Enhancement offers a stronger foundation for retirement income, but it’s essential to integrate these changes into your overall financial planning. While the enhanced CPP provides a significant boost, it’s typically one part of a comprehensive retirement strategy. Relying solely on CPP, even with the enhancements, may not be sufficient to meet all your retirement goals. Therefore, understanding how the enhanced CPP fits into your broader financial picture is crucial for a secure future.
One of the first steps is to review your current financial situation and retirement goals. Consider what kind of lifestyle you envision in retirement and what that will cost. Then, factor in the projected increase from the enhanced CPP. Tools are available through Service Canada and financial advisors that can help you estimate your future CPP benefits based on your earning history and expected contributions under the new rules. This estimate will give you a clearer idea of the income gap you might need to fill with other savings and investments.
Key Considerations for Your Retirement Plan
Review Your Savings: Assess your Registered Retirement Savings Plans (RRSPs), Tax-Free Savings Accounts (TFSAs), and any other personal investments. The enhanced CPP can reduce the pressure on these accounts, but they remain vital for a comfortable retirement.
Consult a Financial Advisor: A professional can help you understand the specifics of your situation, project your future CPP benefits, and create a personalized retirement plan that incorporates the enhanced CPP. They can also advise on strategies to maximize your overall retirement income.
Understand Your Contribution History: The amount you receive from the enhanced CPP is directly tied to your contributions. Regularly check your Statement of Contributions from Service Canada to ensure accuracy and understand your progress.
Consider Your Retirement Age: The age at which you start receiving CPP benefits (between 60 and 70) significantly impacts the monthly amount. The enhanced CPP also factors into these calculations, so it’s worth exploring different scenarios.
The Canada Pension Plan Enhancement is a powerful tool for improving retirement security. By actively engaging with your financial planning, understanding these changes, and making informed decisions about your savings and investments, you can leverage the enhanced CPP to build a more robust and confident financial future. It’s about taking control and ensuring your retirement dreams become a reality.
Frequently Asked Questions
What exactly is the Canada Pension Plan Enhancement?
The Canada Pension Plan Enhancement is a series of changes introduced in 2019 to gradually increase CPP contributions and benefits. Its goal is to provide future retirees with more income, aiming to replace one-third of average work earnings instead of one-quarter, potentially boosting retirement income by 15% for long-term contributors.
When did the CPP Enhancement start and when will it be fully implemented?
The enhancement began in 2019 with gradual increases in contribution rates. The second phase, introducing a second earnings ceiling, started in 2024. The full impact on retirement benefits will be realized over many decades, primarily for those who contribute for 40 years under the enhanced rules.
Who pays for the CPP Enhancement?
Both employees and employers contribute to the CPP Enhancement through increased contribution rates on a larger portion of earnings. Self-employed individuals pay both the employer and employee portions. These additional contributions directly fund the enhanced benefits.
How much more will I contribute to the CPP?
The amount of your increased contribution depends on your earnings. There was a gradual increase in the first contribution rate from 2019-2023. Starting in 2024, a new, second contribution rate applies to earnings between the Year’s Maximum Pensionable Earnings (YMPE) and the new Year’s Additional Maximum Pensionable Earnings (YAMPE).
Will the CPP Enhancement affect my other CPP benefits, like disability?
Yes, the Canada Pension Plan Enhancement extends beyond just retirement benefits. It also aims to increase other CPP benefits, including disability benefits and survivor benefits, providing broader financial protection for Canadians and their families.
Official Resources
[Service Canada – Canada Pension Plan (CPP)](https://www.canada.ca/en/services/benefits/publicpensions/cpp.html)
[Government of Canada – Overview of the CPP Enhancement](https://www.canada.ca/en/revenue-agency/services/tax/businesses/topics/payroll/payroll-deductions-contributions/canada-pension-plan-cpp/cpp-enhancement.html)
[Department of Finance Canada – Canada Pension Plan Enhancement](https://www.canada.ca/en/department-finance/services/retirement-income/canada-pension-plan-enhancement.html)
[Financial Consumer Agency of Canada – Retirement Planning](https://www.canada.ca/en/financial-consumer-agency/services/retirement-planning.html)
Conclusion
The Canada Pension Plan (CPP) Enhancement represents a significant and positive shift in Canada’s approach to retirement security. By gradually increasing contributions and expanding the earnings ceiling, the enhanced CPP is designed to provide a more substantial income stream for future retirees, with projections indicating a potential 15% increase in benefits over the next decade for long-term contributors. This proactive measure ensures the CPP remains a robust and reliable foundation for your golden years, offering greater financial stability and peace of mind.
Understanding these changes is not just about knowing what’s happening; it’s about empowering yourself to plan more effectively for your future. While the enhanced CPP provides a stronger base, it is an integral part of a larger retirement strategy. We encourage you to review your personal financial situation, consult with a financial advisor, and utilize the official resources available to gain a comprehensive understanding of how these enhancements will specifically impact your retirement journey. By taking these steps, you can confidently navigate your financial planning and look forward to a more secure and comfortable retirement thanks to the Canada Pension Plan Enhancement.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.