2026 CPP Enhancements: What 1.5% More Means for Retirement
Discover how the 2026 Canada Pension Plan enhancements, particularly the additional 1.5% contribution, will shape your retirement. Learn about the changes and how to prepare for a more secure financial future.
By: Michael Sete on August 22, 2026
Navigating the 2026 Canada Pension Plan Enhancements: What 1.5% More Means for Your Retirement
The landscape of retirement planning in Canada is continually evolving, and a significant change on the horizon is the 2026 CPP enhancements. These updates to the Canada Pension Plan (CPP) are designed to provide greater financial security for Canadians in their golden years, but they also bring new considerations for both employers and employees. Understanding these changes, particularly the additional 1.5% contribution, is crucial for anyone looking to plan effectively for their future retirement income.
The goal of these enhancements is to increase the amount of income Canadians receive in retirement, helping to address concerns about the adequacy of future pensions. This means that while contributions will see a modest rise, the long-term benefit for retirees is projected to be substantial. Preparing for these adjustments now can help you maximize your benefits and ensure a more stable financial future. Let’s delve into what these changes entail and how you can best navigate them.
Understanding the Second Additional CPP Contribution (CPP2)
The Canada Pension Plan (CPP) is undergoing a multi-stage enhancement process, with the second additional CPP contribution, often referred to as CPP2, set to take effect in 2024 and fully implemented by 2026. This phase introduces a new earnings ceiling, meaning contributions will apply to a wider range of income. The initial CPP enhancement began in 2019, gradually increasing contribution rates and benefits. The 2026 changes build upon this foundation, aiming to further strengthen the plan’s ability to provide a more robust retirement income.
Essentially, the CPP2 introduces a second earnings bracket for contributions. Currently, there’s a year’s maximum pensionable earnings (YMPE), and contributions are made up to that limit. The new enhancement creates a year’s additional maximum pensionable earnings (YAMPE), which will be 14% higher than the YMPE in 2024 and 7% higher in 2025 and beyond. This expansion of the contribution base is a key component of how the government plans to fund increased future benefits. It ensures that higher earners also contribute more, thereby bolstering the overall sustainability and generosity of the plan.
These changes are not minor adjustments; they represent a fundamental shift in how CPP contributions are calculated for many Canadians. The intent is clear: to ensure that the CPP remains a cornerstone of retirement security for generations to come. For individuals, this means a slight increase in payroll deductions, but it also translates into a promise of higher pension payments later on. Employers will also see their contribution obligations rise, requiring careful budgeting and payroll adjustments to accommodate the new structure.
The Impact of the Additional 1.5% Contribution Rate
The additional 1.5% contribution rate is a core element of the 2026 CPP enhancements, directly influencing both current paychecks and future retirement benefits. For earnings above the first earnings ceiling (YMPE) but below the new second earnings ceiling (YAMPE), both employees and employers will contribute an additional 4% each, totaling 8% on those earnings. This is on top of the existing 5.95% contribution rate for earnings up to the YMPE. The 1.5% figure often cited refers to the overall increase in contributions when considering the expanded earnings range and the new rate structure.
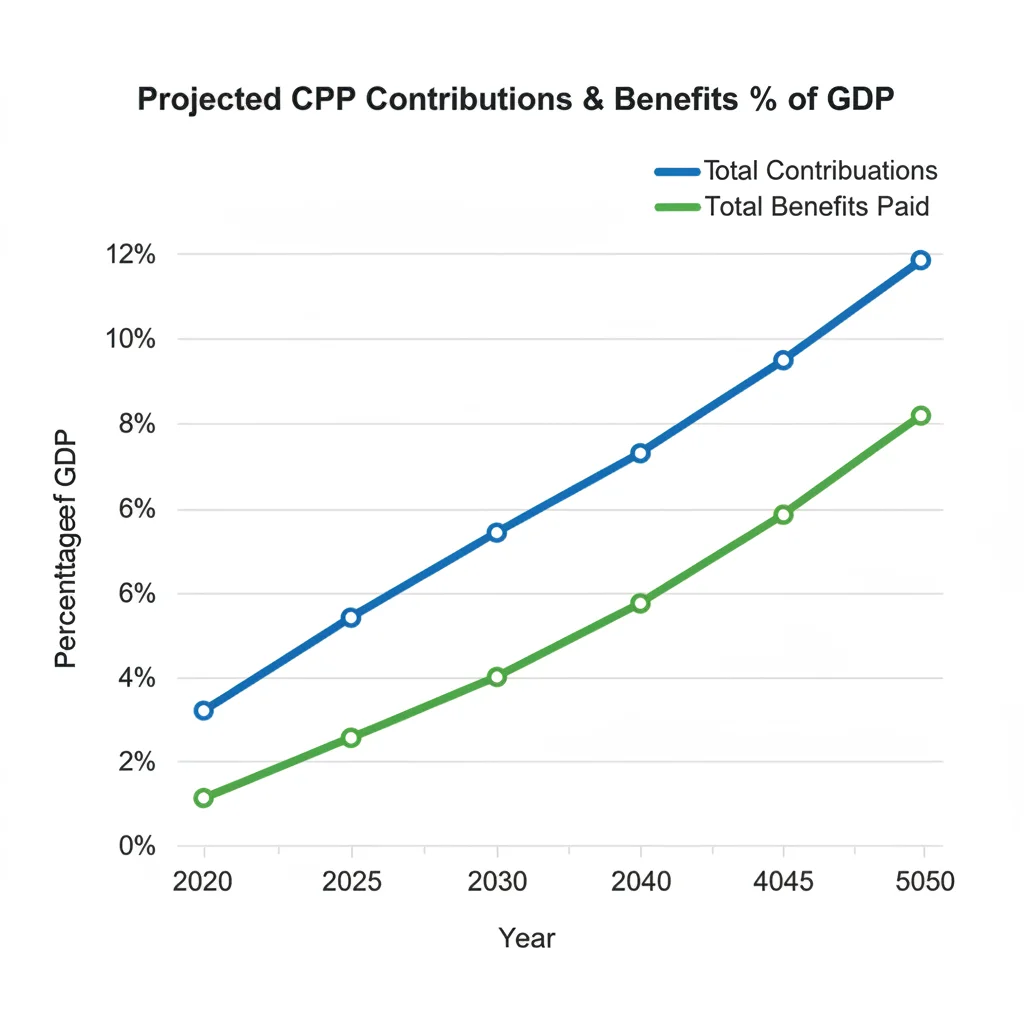
This means that if your income falls within the new, higher earnings bracket, a portion of your salary will be subject to this additional contribution. While this might seem like a small amount on each paycheck, it accumulates significantly over a working career. The beauty of this system is that every dollar contributed during your working years directly enhances your future CPP payout. The government projects that these increased contributions will lead to a significant boost in retirement income for future retirees, potentially increasing their CPP benefits by up to 50% compared to the previous system.
It’s important to remember that these contributions are mandatory for most working Canadians and are automatically deducted from your pay. Self-employed individuals will be responsible for both the employee and employer portions of these contributions. Understanding this increased contribution rate is vital for personal budgeting and long-term financial planning, as it directly affects your net income today and your financial well-being tomorrow. The enhanced CPP aims to provide a more robust safety net, reducing reliance on other forms of savings for a comfortable retirement.
Who Will Be Affected by the New CPP Rules?
The new Canada Pension Plan rules, especially the 2026 CPP enhancements, will have a broad impact across the Canadian working population. Essentially, anyone who contributes to the CPP and earns above the current Year’s Maximum Pensionable Earnings (YMPE) will see changes to their contributions and, consequently, their future benefits. This includes a significant portion of the middle and higher-income workforce. Individuals earning below the YMPE will continue to contribute at the existing rate, and their benefits will also see a proportionate increase due to the overall enhancement of the plan.
Employers across all sectors will also be directly affected. They will be responsible for matching the increased employee contributions on earnings between the YMPE and the new Year’s Additional Maximum Pensionable Earnings (YAMPE). This means adjustments to payroll systems, increased payroll expenses, and a need for clear communication with employees about these changes. Small businesses, in particular, will need to factor these increased costs into their operational budgets and financial forecasts.
Furthermore, self-employed individuals will bear the full weight of both the employee and employer portions of these enhanced contributions. This requires careful financial planning and budgeting to ensure compliance and to avoid any surprises. Future retirees stand to gain the most, as the primary objective of these enhancements is to provide a more substantial and reliable income stream during retirement. The additional contributions made today are investments in a more secure financial future for millions of Canadians.
Strategies for Adapting to the Enhanced CPP
Adapting to the enhanced CPP, particularly the 2026 CPP enhancements, involves proactive planning and understanding how these changes integrate with your broader financial strategy. While the increased contributions are mandatory, recognizing their long-term benefits can help you adjust your personal finances effectively. One key strategy is to review your current budget and savings plan. The slight increase in deductions means a small reduction in take-home pay for some, so ensuring your budget can absorb this without impacting essential expenses is important. Consider this a forced savings mechanism that will pay off significantly in retirement.
Another crucial step is to integrate your expected enhanced CPP benefits into your overall retirement income projections. While the exact figures will depend on your earnings history, you can generally anticipate higher CPP payments than under the old system. This might allow you to adjust your personal savings goals, perhaps shifting some focus to other investment vehicles or accelerating debt repayment. However, it’s vital not to become complacent; the CPP is a foundational pillar, but personal savings, RRSPs, and TFSAs remain critical for a truly comfortable retirement.
Key Adaptation Strategies:
Review Your Budget: Adjust for increased CPP deductions to maintain financial stability.
Update Retirement Projections: Factor in higher expected CPP benefits to refine your overall retirement income goals.
Maximize Other Savings: Continue to contribute to RRSPs and TFSAs, using the enhanced CPP as a solid base.
Consult a Financial Advisor: Get personalized advice on how the CPP changes affect your unique financial situation and investment strategy.
Understand Your Statement: Regularly review your CPP Statement of Contributions to ensure accuracy and estimate future benefits.
By taking these steps, you can turn the mandatory adjustments into an opportunity to strengthen your financial resilience and build a more secure future. The enhanced CPP is a positive development, but its full potential is realized when combined with thoughtful personal financial management.
Long-Term Benefits for Future Retirees
The long-term benefits of the 2026 CPP enhancements for future retirees are substantial and represent a significant step towards improving retirement security in Canada. The primary advantage is a projected increase in the amount of income individuals will receive from their CPP pension. For those who contribute to the enhanced CPP for 40 years, their retirement income could be up to 50% higher than what they would have received under the old CPP rules. This means a more comfortable and financially stable retirement for many Canadians, reducing the pressure on personal savings alone.
Beyond just the increased dollar amount, the enhanced CPP provides a greater sense of predictability and reliability in retirement income. As a government-backed plan, CPP benefits are indexed to inflation, meaning their purchasing power is protected over time. This offers a stable income floor that can withstand economic fluctuations, a crucial factor for long-term financial planning. The additional contributions made now are an investment in this stable, inflation-protected income stream for your later years, providing peace of mind.
Furthermore, the enhancements aim to address the changing nature of work and ensure that the CPP remains relevant and robust for future generations. With fewer people having access to defined benefit pension plans through their employers, the strengthened CPP serves as an even more vital component of a comprehensive retirement strategy. It helps bridge potential income gaps and ensures that all working Canadians have a foundational layer of retirement income, regardless of their employment type or industry. This collective effort today translates into improved individual security tomorrow.
Frequently Asked Questions
What is the main goal of the 2026 CPP enhancements?
The primary goal is to increase the amount of retirement income Canadians receive from the Canada Pension Plan, aiming to provide greater financial security in their later years. It addresses concerns about the adequacy of future pensions for a growing population.
How much more will I contribute under the new rules?
For earnings above the first earnings ceiling (YMPE) but below the new second earnings ceiling (YAMPE), both employees and employers will contribute an additional 4% each, totaling 8% on those specific earnings. This is in addition to the existing contribution rates.
Will the enhanced CPP replace my personal savings?
No, the enhanced CPP is designed to complement, not replace, personal savings vehicles like RRSPs and TFSAs. While it provides a more robust foundation for retirement income, personal savings remain crucial for achieving a truly comfortable and customized retirement.
When do the full 2026 CPP enhancements take effect?
The enhancements are being phased in, with the second additional CPP contribution (CPP2) starting in 2024 and fully implemented by 2026. This means the full impact on contributions and benefits will be realized by 2026.
Are self-employed individuals affected differently?
Yes, self-employed individuals are responsible for paying both the employee and employer portions of these enhanced CPP contributions. This requires careful budgeting and financial planning on their part to ensure compliance with the new rules.
The 2026 CPP enhancements represent a pivotal moment for retirement planning in Canada. By understanding the additional 1.5% contribution and its broader implications, Canadians can proactively adjust their financial strategies to leverage these changes effectively. While the immediate impact involves slightly higher payroll deductions for some, the long-term benefits of a more secure and substantial retirement income are clear. These enhancements reinforce the CPP’s role as a cornerstone of financial stability for future retirees, offering inflation-protected benefits that will significantly contribute to a comfortable post-work life.
It is essential for both employees and employers to stay informed about these evolving rules and to integrate them into their financial planning. Reviewing personal budgets, updating retirement projections, and consulting with financial professionals are all valuable steps to ensure you are well-prepared. The enhanced CPP is a collective investment in the future well-being of Canadians, promising a stronger safety net for generations to come. By taking an active role in understanding and adapting to these changes, you can ensure a more predictable and prosperous retirement journey.