Pension Splitting for Canadian Seniors: Boost Your Income
Canadian pension splitting offers a powerful way for seniors to significantly optimize their retirement income. This strategy can reduce your overall tax burden and potentially increase your net household income by up to 30%.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
Pension Splitting for Canadian Seniors: Optimizing Your Income by Up to 30%
For many Canadian seniors, understanding and utilizing strategies like Canadian pension splitting is key to maximizing retirement income. This often-overlooked tax planning tool can significantly reduce your household’s overall tax burden, potentially boosting your net income by as much as 30%. It’s a powerful way to ensure more of your hard-earned pension stays in your pocket, allowing for a more comfortable and secure retirement.
Pension splitting allows a higher-income spouse or common-law partner to allocate up to 50% of their eligible pension income to their lower-income partner. This strategy can lead to substantial tax savings, especially when there’s a notable difference in income levels between the two individuals. By balancing incomes, the household can take advantage of lower tax brackets and claim more tax credits, ultimately leading to a healthier financial outlook. Let’s delve into the specifics of how Canadian pension splitting works and how you can benefit.
Understanding Eligible Pension Income for Splitting
When we talk about Canadian pension splitting, it’s crucial to first define what exactly constitutes “eligible pension income.” Not all retirement income can be split, and understanding the distinctions is the first step toward effectively using this strategy. The Canada Revenue Agency (CRA) has specific rules about which types of income qualify, and these rules can vary depending on your age.
For individuals aged 65 or older, a broader range of income sources is considered eligible. This includes payments from a registered pension plan (RPP), annuities from a registered retirement savings plan (RRSP) or registered retirement income fund (RRIF), and even certain foreign pension payments. This wider scope means that most seniors will find a significant portion of their retirement income eligible for splitting. However, it’s important to note that Old Age Security (OAS) and Canada Pension Plan (CPP) benefits are not included in this category, as they have their own splitting mechanisms.
For those under 65, the definition of eligible pension income is more restrictive. Generally, only payments received from a registered pension plan (RPP) are considered eligible for splitting. This means that if you’re retired early and receiving income from an RRSP annuity or RRIF, you typically cannot split that income until you turn 65. Understanding these age-based distinctions is vital for accurate tax planning and ensures you are applying the pension splitting rules correctly to your specific situation. Always confirm your income sources with CRA guidelines.
How Pension Splitting Reduces Your Tax Burden
The primary benefit of Canadian pension splitting lies in its ability to significantly reduce your overall household tax burden. Canada operates on a progressive tax system, meaning that higher incomes are taxed at higher rates. When one spouse has a much higher income than the other, a large portion of their earnings can fall into higher tax brackets, leading to a substantial tax bill. Pension splitting helps to mitigate this imbalance by shifting income from the higher-earning spouse to the lower-earning one.
By transferring up to 50% of eligible pension income, the higher-income spouse’s taxable income decreases, potentially moving them into a lower tax bracket. Simultaneously, the lower-income spouse’s taxable income increases, but often remains within a lower bracket, or at least avoids pushing the household into a significantly higher bracket overall. This equalization of income allows the couple to take greater advantage of lower marginal tax rates that apply to smaller incomes. The combined effect is a reduction in the total amount of tax paid by the household, rather than just shifting the tax burden from one person to another without overall benefit.
Beyond the direct tax rate reduction, pension splitting can also unlock or increase access to various non-refundable tax credits. Many federal and provincial tax credits, such as the age amount or medical expense tax credit, are income-tested or become more valuable when incomes are lower. By balancing incomes through pension splitting, couples can maximize these credits, further reducing their net tax payable. This strategic move can lead to tangible savings, freeing up more money for your retirement lifestyle or other financial goals. It’s a smart way to optimize your financial resources.
Step-by-Step Guide to Implementing Pension Splitting
Implementing Canadian pension splitting is a straightforward process, but it requires careful attention to detail during tax season. It’s not an automatic process; you and your spouse or common-law partner must elect to split the pension income each year. This election is made when you file your annual income tax returns, typically using specific forms provided by the Canada Revenue Agency. Understanding these steps ensures you correctly claim the benefit.
Key Steps for Pension Splitting
Determine Eligibility: First, confirm that the income you wish to split qualifies as eligible pension income, as discussed earlier. Remember that age plays a significant role in what is considered eligible.
Agree on the Split Amount: You and your partner must agree on the percentage of eligible pension income to split, up to a maximum of 50%. This decision should be based on which split provides the greatest tax advantage for your household.
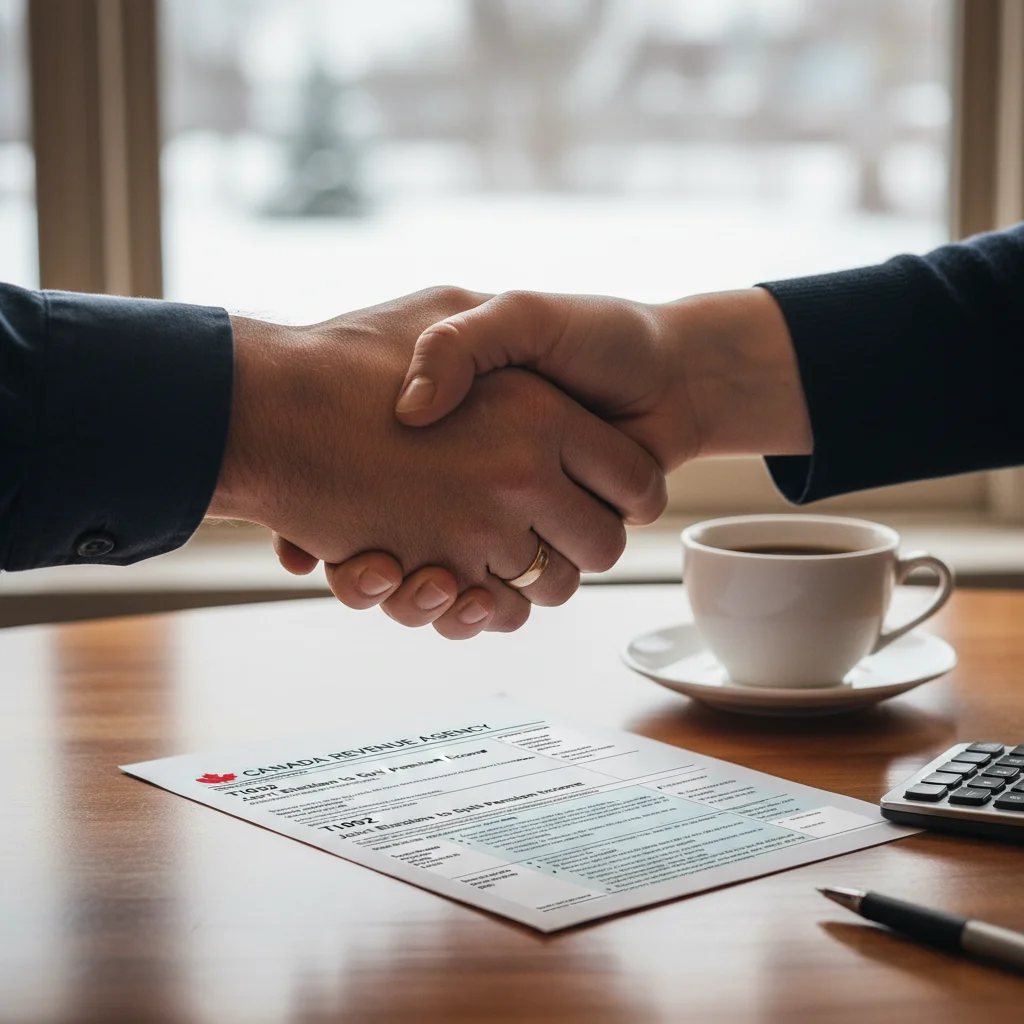
Complete Form T1032: Both you and your spouse or common-law partner must complete and sign Form T1032, “Joint Election to Split Pension Income.” This form is crucial as it formally notifies the CRA of your election to split pension income.
File with Tax Returns: Attach the completed Form T1032 to both your and your spouse’s income tax returns. Each partner must also report their respective portion of the split pension income on their individual tax returns. The higher-income spouse will deduct the amount transferred, and the lower-income spouse will report it as income.
Keep Records: Always retain copies of Form T1032 and all supporting tax documents for your records. This is important for future reference or in case the CRA requests verification.
By following these steps, you can effectively implement pension splitting and realize the tax benefits. It’s a yearly decision, so you have the flexibility to adjust the split percentage based on your income situation each tax year. Professional advice can be helpful to ensure optimal results.
Potential Benefits Beyond Tax Savings
While the primary allure of Canadian pension splitting is undoubtedly the significant tax savings, its advantages extend beyond just reducing your tax bill. This strategic income allocation can have several other positive impacts on your financial well-being in retirement. Understanding these broader benefits can help you appreciate the full value of this planning tool and how it contributes to a more secure financial future.
One notable benefit is the potential to reduce or avoid the Old Age Security (OAS) clawback. The OAS clawback occurs when your net income exceeds a certain threshold, leading to a reduction in your OAS benefits. By splitting pension income, the higher-income spouse’s individual net income decreases, which can help them stay below the OAS clawback threshold. This means you get to keep more of your government benefits, which are a vital component of many seniors’ retirement income. It’s a way to protect your overall income streams from erosion.
Furthermore, pension splitting can impact eligibility for other income-tested benefits and credits. Many provincial benefits, prescription drug programs, or subsidized services are tied to individual income levels. By balancing incomes, you might find that both partners become eligible for benefits they previously couldn’t access, or that they qualify for a higher level of support. This can lead to additional savings on healthcare costs, housing, or other essential services, further enhancing your disposable income. It’s about optimizing your entire financial picture, not just one aspect.
Common Mistakes to Avoid and Expert Tips
While Canadian pension splitting offers considerable advantages, it’s not without its nuances. Making common mistakes can negate the benefits or even lead to complications with the Canada Revenue Agency. Being aware of these pitfalls and following expert advice can ensure you maximize your savings and avoid any unnecessary headaches during tax season. Careful planning and attention to detail are paramount when dealing with your retirement income.
One common mistake is failing to complete and submit Form T1032 correctly. This form is mandatory for pension splitting, and if it’s missing or improperly filled out, the CRA will not process your election. Another error is assuming all retirement income is eligible for splitting; as discussed, certain types of income, especially for those under 65, do not qualify. It’s crucial to verify your income sources against CRA guidelines each year. Also, some couples simply split 50% without analyzing if that’s the optimal percentage for their specific income levels, potentially missing out on further tax efficiencies.
To ensure you’re making the most of pension splitting, consider these expert tips. Always calculate the tax implications of different splitting percentages to find the optimal amount for your household. Software or a tax professional can assist with these calculations. Don’t forget to factor in other income sources and deductions for both spouses, as these can influence the best splitting strategy. Finally, review your pension splitting election annually, as your income, tax laws, and life circumstances can change. An annual review ensures you continue to benefit from this powerful tax-saving tool. Staying informed and proactive is your best defense against errors.
Frequently Asked Questions
What types of pension income can be split in Canada?
Eligible pension income for splitting includes payments from a registered pension plan (RPP) at any age. For those 65 or older, it also includes annuities from RRSPs or RRIFs, and certain foreign pension payments. Canada Pension Plan (CPP) and Old Age Security (OAS) have their own separate splitting rules and are not included in this general pension splitting.
Do both spouses need to be seniors to split pension income?
No, only the spouse receiving the eligible pension income needs to meet the age criteria for that specific income type. For instance, if one spouse is 60 and receives RPP income, they can split it with their 60-year-old spouse. However, if the income is from an RRIF, the recipient must be 65 or older for it to be eligible for splitting.
How do I make the election to split pension income?
To elect to split pension income, you and your spouse or common-law partner must complete and sign Form T1032, “Joint Election to Split Pension Income,” each year. This form must then be filed along with both of your annual income tax returns to notify the Canada Revenue Agency of your decision.
Can pension splitting affect other government benefits?
Yes, pension splitting can significantly impact eligibility for other income-tested government benefits and credits. By lowering the higher-income spouse’s net income, it can help reduce or avoid the Old Age Security (OAS) clawback and may increase eligibility for various federal and provincial tax credits or social programs.
Is it possible to change the percentage of pension income split each year?
Absolutely. Pension splitting is an annual election, meaning you can choose to split a different percentage (up to 50%) each tax year. This flexibility allows you to adjust your strategy based on changes in your income, your spouse’s income, or evolving tax laws, ensuring you always optimize your household’s tax situation.
Canadian pension splitting stands out as a remarkably effective strategy for seniors looking to optimize their retirement income and significantly reduce their tax burden. By allowing higher-income spouses to transfer up to 50% of eligible pension income to their lower-income partners, households can leverage Canada’s progressive tax system to their advantage. This not only leads to direct tax savings but also offers broader benefits, such as mitigating the OAS clawback and enhancing eligibility for other valuable income-tested benefits and credits.
The process, while requiring annual election via Form T1032, is straightforward once understood. Avoiding common pitfalls, such as incorrect form submission or misidentifying eligible income, is crucial for success. Regularly reviewing your financial situation and seeking professional advice can ensure you’re making the most of this powerful tool. By strategically implementing Canadian pension splitting, you can unlock substantial savings, potentially increasing your net household income by up to 30%, and secure a more comfortable and financially stable retirement. Don’t leave money on the table; explore how pension splitting can work for you.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.