CPP Enhancements 2026: What Changes Mean for Your Retirement
Explore the upcoming Canada Pension Plan (CPP) enhancements in 2026 and their potential impact on your retirement income. This guide breaks down the changes, helping you understand how to plan for a more secure financial future in Canada.
By: Michael Sete on August 22, 2026
The Canada Pension Plan (CPP) is a cornerstone of retirement security for millions of Canadians. As we look towards the future, significant changes are on the horizon, specifically the CPP enhancements 2026. These upcoming adjustments are designed to provide greater financial stability for future retirees, reflecting an evolving economic landscape and the needs of an aging population. Understanding these enhancements is crucial for anyone currently contributing to the plan, nearing retirement, or simply planning for their long-term financial well-being.
The 2026 changes build upon previous enhancements, aiming to increase the amount of income Canadians receive in retirement. This article will delve into the specifics of these enhancements, explaining what they mean for your contributions, your future benefits, and how you can best prepare. By gaining a clear understanding of the CPP enhancements 2026, you can make informed decisions about your savings and investment strategies, ensuring a more comfortable and secure retirement.
Understanding the Second Additional CPP Contribution (AAC2)
The 2026 CPP enhancements introduce a pivotal change known as the Second Additional CPP Contribution, or AAC2. This new contribution level is designed to further boost retirement benefits for higher earners. Up until now, there was a maximum amount of earnings on which you contributed to the CPP, known as the Year’s Maximum Pensionable Earnings (YMPE). The AAC2 effectively creates a second earnings ceiling, meaning that individuals earning above the YMPE will contribute a small percentage on a portion of their income that was previously exempt from CPP contributions.
This second tier of contributions will apply to earnings between the existing YMPE and a new, higher threshold called the Year’s Additional Maximum Pensionable Earnings (YAMPE). The YAMPE will be set at 14% above the YMPE in 2024 and 8% above the YMPE in 2025 and subsequent years. The goal is to ensure that those with higher lifetime earnings also receive a proportionally higher CPP benefit in retirement, making the system more robust and equitable across different income brackets. It’s a significant step towards bolstering the financial security of a broader range of retirees.
For employees, this means both you and your employer will contribute to this second tier. Self-employed individuals will contribute both the employee and employer portions, as they do with the primary CPP contributions. These additional contributions are mandatory for eligible earnings and are intended to directly fund the increased benefits that will eventually be paid out. It’s important to recognize that while contributions will increase for some, the long-term benefit is a more substantial retirement income, helping to mitigate potential financial shortfalls in later life.
Who Will Be Affected by the 2026 Changes?
The CPP enhancements 2026 will have a broad impact across the Canadian workforce, though the degree of impact will vary depending on an individual’s income level and career stage. Primarily, individuals whose earnings are above the Year’s Maximum Pensionable Earnings (YMPE) will see the most direct effect on their contributions. If your income falls below the YMPE, your CPP contributions will remain largely as they are under the existing enhanced CPP framework, meaning you won’t contribute to the new Second Additional CPP Contribution (AAC2).
However, for those with earnings above the YMPE, both employees and their employers will begin contributing to the AAC2. This means a slight increase in payroll deductions for these higher earners. It’s important to remember that these increased contributions are not simply a tax; they are investments into a larger future retirement pension. Over a career, these additional contributions are designed to accumulate into a significantly higher monthly benefit once you retire, offering greater financial comfort and security.
Younger Canadians and those early in their careers stand to benefit most from these enhancements, as they will have more years to contribute to the AAC2. This longer contribution period will allow them to build up a more substantial additional pension amount. Older workers closer to retirement might see a smaller, but still noticeable, increase in their future benefits, depending on how many years they contribute to the AAC2 before retiring. Essentially, anyone who contributes to the CPP and earns above the YMPE will eventually see a positive impact on their retirement income from these enhancements.
Projected Impact on Retirement Income
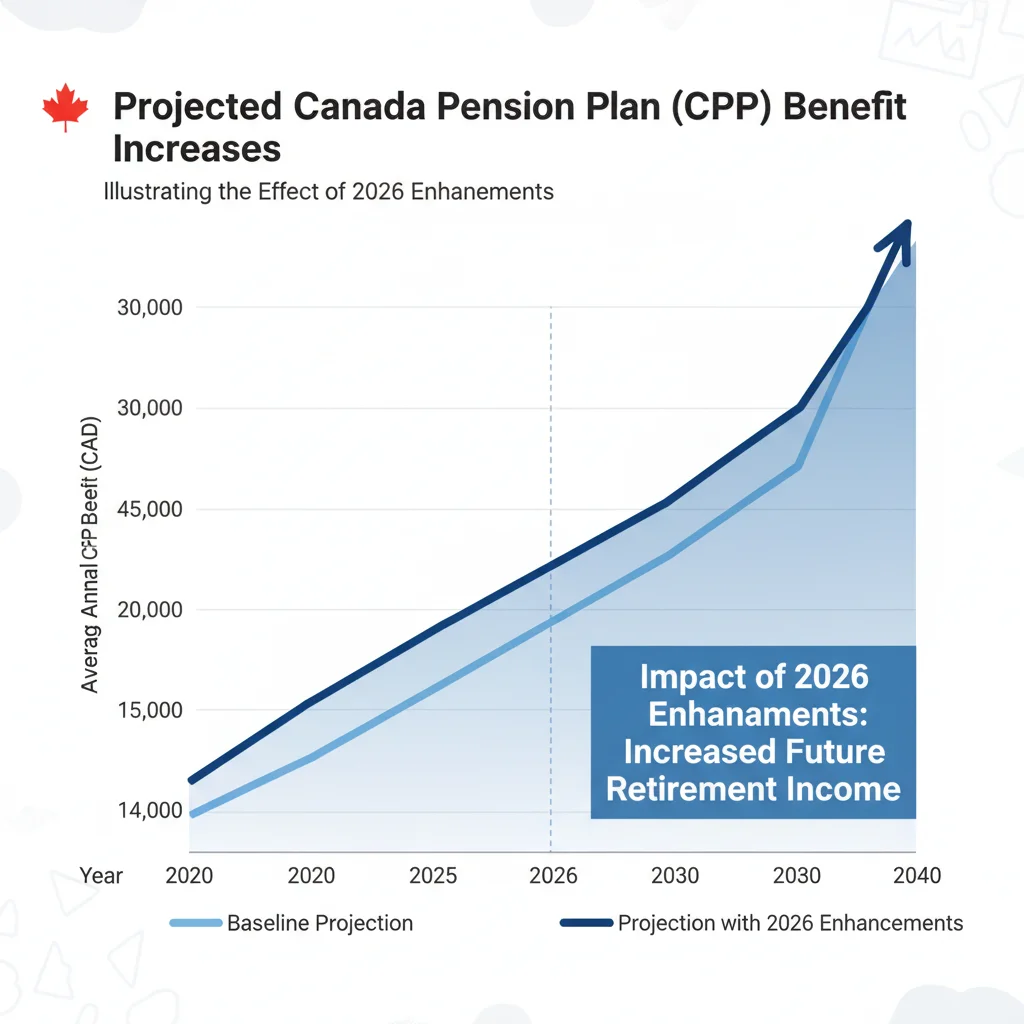
The primary goal of the CPP enhancements 2026 is to increase the amount of retirement income Canadians receive, particularly for those with higher lifetime earnings. With the introduction of the Second Additional CPP Contribution (AAC2), future retirees can expect to see a more substantial monthly pension cheque. This additional pension amount will be calculated based on the contributions made to the AAC2, adding to the benefits accumulated from the primary CPP contributions.
For a Canadian who consistently earns above the Year’s Additional Maximum Pensionable Earnings (YAMPE) throughout their career, the enhanced CPP could eventually replace up to one-third of their average lifetime earnings, up to the YAMPE. This is a notable increase from the previous target of replacing one-quarter of average lifetime earnings up to the YMPE. While the full impact will only be realized by those who contribute to the enhanced CPP for many years, the direction is clear: a more generous and robust pension system.
Illustrative Benefit Increases
Higher Earners: Individuals consistently earning above the YAMPE could see their maximum CPP benefit increase significantly over time, potentially by thousands of dollars annually compared to the old system.
Long-Term Contributors: Those who contribute to the enhanced CPP, including the AAC2, for 40 years will experience the full effect of the increased replacement rate, leading to a much higher retirement income.
Early Retirees: While benefits are still reduced for early retirement, the enhanced base amount means even a reduced early pension will be higher than it would have been under the old rules.
It’s crucial to understand that these benefits are not immediate. The full effect of the enhancements will gradually phase in over decades as individuals contribute more to the expanded plan. However, every year of contribution to the AAC2 will incrementally build towards a larger future pension, providing a more secure foundation for retirement.
Planning Your Retirement with Enhanced CPP
Given the upcoming CPP enhancements 2026, it’s an opportune time to revisit and potentially adjust your retirement planning strategies. While the enhanced CPP will provide a more substantial safety net, it’s still intended to be one pillar of your retirement income, alongside personal savings, investments, and potentially workplace pensions. Understanding how these enhanced benefits fit into your overall financial picture is key to achieving your retirement goals.
First, consider your expected earnings trajectory. If you anticipate earning above the Year’s Maximum Pensionable Earnings (YMPE) and subsequently contributing to the Second Additional CPP Contribution (AAC2), factor in the slightly increased contributions. While these deductions will be automatic, being aware of them helps in budgeting and cash flow management. More importantly, project how these additional contributions will translate into a higher CPP benefit in your retirement. Tools and calculators from official government sources can help estimate these future benefits.
Second, use the enhanced CPP as a stronger foundation upon which to build your other retirement savings. If the enhanced CPP is projected to cover a larger portion of your essential retirement expenses, you might adjust your personal savings goals. For example, you might feel more comfortable allocating a slightly smaller percentage of your income to other retirement vehicles, or perhaps you’ll maintain your current savings rate, leading to an even more comfortable retirement. The key is to integrate the enhanced CPP into a holistic plan, ensuring all components work together to meet your desired lifestyle in retirement.
Strategies for Maximizing Your Future CPP Benefits
To truly maximize the benefits from the CPP enhancements 2026, it’s wise to adopt a proactive approach to your career and financial planning. While many aspects of CPP are mandatory, certain choices can influence the total amount you receive in retirement. Understanding these strategies can help you make the most of the enhanced system and secure a more robust financial future.
One key strategy is to ensure consistent contributions throughout your working life, especially if your income allows you to contribute to the Second Additional CPP Contribution (AAC2). The more years you contribute at or above the Year’s Additional Maximum Pensionable Earnings (YAMPE), the higher your eventual retirement benefit will be. This emphasizes the importance of stable employment and maintaining a good income level over your career. If you experience periods of lower income or unemployment, be aware of the impact on your average lifetime earnings, which are used to calculate your CPP.
Another important consideration is the timing of when you start receiving your CPP benefits. While you can begin receiving CPP as early as age 60, your benefits are reduced for each month you take them before age 65. Conversely, delaying your CPP benefits past age 65, up to age 70, results in a higher monthly payment. With the enhanced CPP providing a larger base amount, delaying benefits could lead to an even more significant increase in your monthly income, potentially making a substantial difference over the course of your retirement. This decision should be carefully weighed against your personal financial needs and health considerations.
Finally, keep abreast of any further legislative changes or updates to the CPP. While the 2026 enhancements are set, pension plans can evolve. Regularly checking official government sources for information and consulting with a financial advisor can help you stay informed and adapt your strategies as needed. A well-informed approach will ensure you are always positioned to maximize your CPP benefits.
Frequently Asked Questions
What exactly are the CPP enhancements 2026?
The CPP enhancements 2026 refer to the full implementation of the ‘Second Additional CPP Contribution’ (AAC2). This means that individuals earning above the existing Year’s Maximum Pensionable Earnings (YMPE) will contribute to a new, higher earnings ceiling, leading to increased retirement benefits for these higher earners.
Will my CPP contributions increase in 2026?
Yes, if your annual income is above the Year’s Maximum Pensionable Earnings (YMPE), you will see an increase in your CPP contributions starting in 2026 due to the Second Additional CPP Contribution (AAC2). If your income is below the YMPE, your contributions will remain consistent with the current enhanced CPP rules.
How much more will I get in retirement benefits?
The amount of increased benefits will depend on your lifetime earnings and how many years you contribute to the enhanced CPP, particularly to the AAC2. For those who consistently contribute at the highest levels over many years, the enhanced CPP could replace up to one-third of average lifetime earnings, up to the new Year’s Additional Maximum Pensionable Earnings (YAMPE).
Do these changes affect existing retirees?
Generally, the CPP enhancements primarily benefit those who are currently working and contributing to the plan. Existing retirees typically receive benefits based on the rules and contributions made during their working years. However, all CPP benefits are indexed to inflation, which helps maintain purchasing power.
Where can I find official information about these changes?
For the most accurate and up-to-date information, you should consult official government sources such as Employment and Social Development Canada (ESDC) or the Canada Revenue Agency (CRA) websites. These sites provide detailed explanations and resources regarding CPP contributions and benefits.
The CPP enhancements 2026 represent a significant evolution in Canada’s retirement income system, designed to provide greater financial security for future generations of retirees. By introducing the Second Additional CPP Contribution (AAC2), the government is ensuring that those with higher lifetime earnings will also build a more substantial pension, aiming to replace a larger portion of their pre-retirement income. While this means slightly increased contributions for some, the long-term benefit is a more robust and reliable foundation for retirement.
Understanding these changes is not just an academic exercise; it’s a critical step in effective personal financial planning. Whether you are just starting your career or are nearing retirement, knowing how the enhanced CPP will affect your contributions and future benefits allows you to make informed decisions about your savings, investments, and overall retirement strategy. The goal is to integrate these enhanced benefits into a comprehensive plan that ensures you can enjoy a comfortable and secure retirement, knowing that Canada’s public pension system is evolving to meet the needs of its citizens. Take the time to assess your personal situation, utilize available resources, and plan proactively for a brighter financial future.