The Disability Tax Credit (DTC) offers significant financial relief for Canadians with disabilities. Learn how to navigate the application process, understand eligibility, and unlock an average of $2,500 in annual tax savings. Our guide provides updated tips to help you secure this essential benefit.
By: Michael Sete on August 22, 2026
The Disability Tax Credit (DTC) is a non-refundable tax credit designed to help reduce the income tax burden for individuals with severe and prolonged mental or physical impairments. This crucial federal program can unlock an average of $2,500 in annual savings for eligible Canadians, providing much-needed financial relief. Understanding the intricacies of the application process and keeping up with updated tips is key to accessing this valuable support.
Many Canadians who qualify for the Disability Tax Credit might not even be aware of its existence or the significant financial benefits it offers. The credit aims to offset some of the additional costs that people with disabilities and their supporting family members often face. By taking the time to learn about the DTC and its requirements, you can ensure you or your loved one receives the support deserved, making a tangible difference in daily life and financial stability.
Understanding the Disability Tax Credit Eligibility
Eligibility for the Disability Tax Credit hinges on meeting specific criteria set by the Canada Revenue Agency (CRA). It’s not just about having a medical condition; the condition must be severe and prolonged, meaning it has lasted or is expected to last for a continuous period of at least 12 months. Furthermore, the impairment must significantly restrict one or more basic activities of daily living, or the individual must require life-sustaining therapy.
The CRA evaluates impairments based on their effect on an individual’s ability to perform daily tasks. These activities include walking, feeding, dressing, mental functions necessary for everyday life, speaking, hearing, and vision. It’s important to remember that a medical diagnosis alone doesn’t guarantee eligibility; rather, it’s how the impairment affects your daily life that matters most. This distinction is crucial for both applicants and medical practitioners completing the form.
For example, someone with a severe mobility impairment might struggle with walking, impacting their ability to work or participate in community activities. Similarly, an individual with a severe and prolonged mental impairment might have significant difficulty with memory, problem-solving, or adaptive functioning. The credit also extends to those who receive life-sustaining therapy, such as dialysis or insulin therapy, where the therapy itself takes a considerable amount of time each week to administer.
The CRA also considers cumulative effects of multiple mild restrictions. If an individual has two or more impairments that, when combined, significantly restrict them in performing a basic activity of daily living, they might also qualify. This ‘cumulative effects’ rule recognizes that even seemingly minor issues can create a substantial barrier when combined, emphasizing a holistic view of the applicant’s challenges. Always consult with a medical professional to accurately assess and document these effects.
Navigating the Application Process: Form T2201
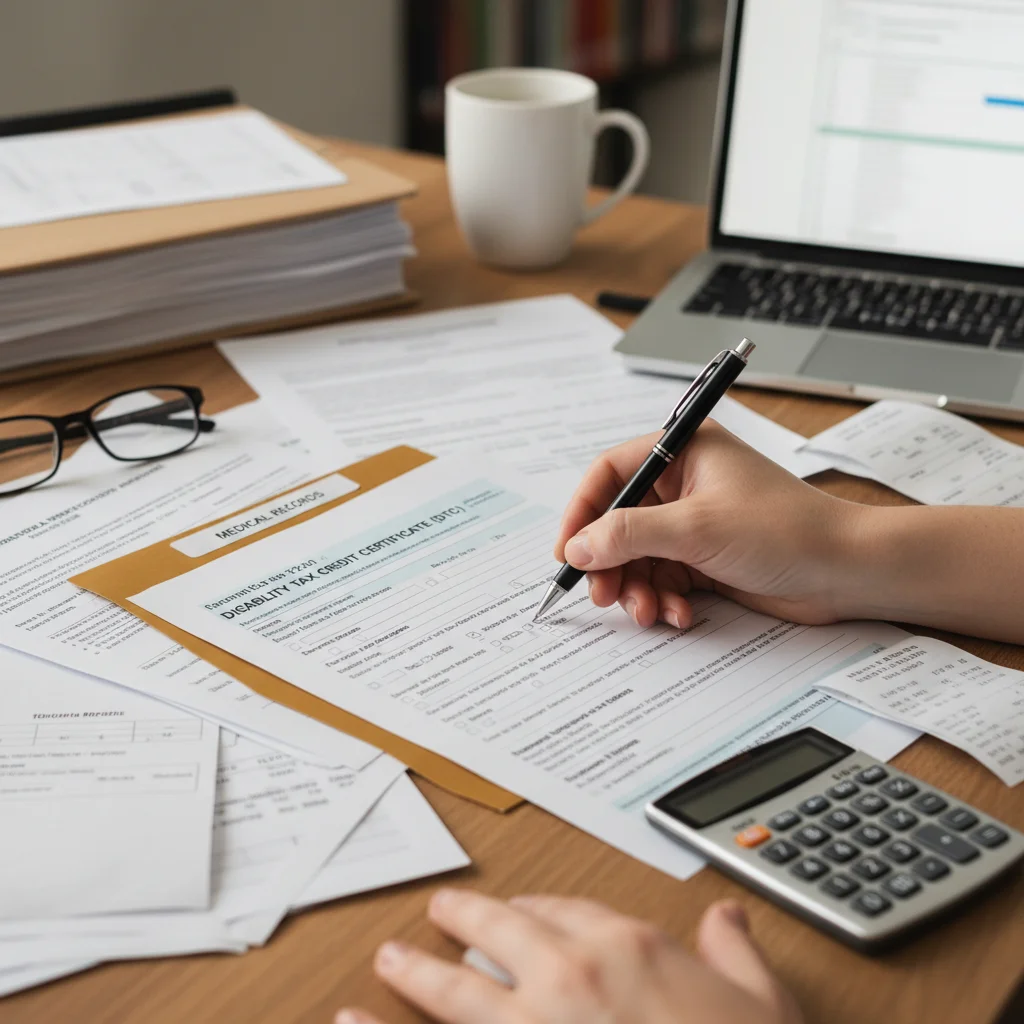
The cornerstone of applying for the Disability Tax Credit is Form T2201, Disability Tax Credit Certificate. This form is divided into two main parts: Part A, which you, the applicant (or a family member on your behalf), must complete, and Part B, which a qualified medical practitioner must fill out. Accuracy and thoroughness in both sections are paramount for a successful application, as any missing information or unclear descriptions can lead to delays or even rejection.
When completing Part A, ensure all personal details are correct and up-to-date. You’ll need to indicate the nature of your impairment and the date it began. If you are applying on behalf of someone else, you must clearly state your relationship to that individual. Take your time to review this section carefully before moving on. Errors here, however minor, can cause unnecessary back-and-forth with the CRA, prolonging the application timeline.
Part B is where your medical practitioner provides detailed information about your impairment. This section requires a doctor, nurse practitioner, audiologist, occupational therapist, optometrist, physiotherapist, psychologist, or speech-language pathologist to certify the nature and severity of your condition. They must describe how the impairment affects your daily life, specifically addressing the criteria laid out by the CRA for basic activities of daily living or life-sustaining therapy. Encourage your practitioner to be as specific and descriptive as possible, using clear language to explain the functional limitations. Generic statements are often insufficient.
It’s beneficial to have a discussion with your medical practitioner before they complete Part B. Explain to them why you believe you qualify for the DTC and provide any documentation or personal notes that illustrate the impact of your impairment on your daily activities. This collaborative approach can help your practitioner provide a more comprehensive and compelling assessment, significantly strengthening your application. Once both parts are complete, you can submit the form to the CRA, either online through My Account or by mail.
Maximizing Your Disability Tax Credit Benefits
Once approved for the Disability Tax Credit, the benefits can extend beyond just reducing your current year’s income tax. The DTC can be claimed retroactively for up to 10 previous tax years, provided you met the eligibility criteria during those years. This retroactive claim can result in a substantial refund, often a pleasant surprise for new recipients. To claim retroactively, you’ll need to request an adjustment to your past tax returns, which can be done through your CRA My Account or by mailing a T1-ADJ form.
The DTC also acts as a gateway to other important federal programs and benefits. For instance, being eligible for the DTC is a prerequisite for opening a Registered Disability Savings Plan (RDSP). An RDSP is a long-term savings plan designed to help individuals with disabilities and their families save for the future. Contributions to an RDSP can attract significant government grants and bonds, making it a powerful tool for financial security. Even modest contributions can grow substantially with government assistance.
Furthermore, if the person with the disability does not need the full amount of the credit to reduce their own tax payable to zero, the unused portion can be transferred to a supporting family member. This could be a spouse, common-law partner, parent, grandparent, child, grandchild, brother, sister, aunt, uncle, niece, or nephew. This transferability ensures that the financial relief reaches the family members who are most directly supporting the individual with the disability, further amplifying the overall benefit. Understanding these additional benefits is key to truly maximizing the impact of the DTC.
It’s also important to keep your medical information updated with the CRA if there are significant changes to your condition. While initial approval can last for several years, periodic reviews may occur. Being proactive in providing updated medical documentation can help ensure continuous eligibility. Always keep copies of all submitted forms and supporting documents for your records, as this can be invaluable if questions arise later or if you need to reapply in the future.
Common Reasons for Application Delays or Denials
While the Disability Tax Credit is a vital program, applications can sometimes face delays or even outright denial. Understanding the common pitfalls can help you avoid them and increase your chances of a smooth approval process. One of the primary reasons for delays is incomplete or unclear information on Form T2201. If either Part A or Part B lacks necessary details, the CRA will likely send it back for clarification, adding weeks or months to the processing time.
Another frequent issue arises when the medical practitioner’s description of the impairment is insufficient. The CRA needs a clear explanation of how the condition significantly restricts basic activities of daily living, not just a diagnosis. For instance, stating ‘diabetic’ is not enough; the practitioner must explain how the diabetes impacts daily functions, such as requiring life-sustaining therapy for a specific duration each week. Vague language or a lack of detail about functional limitations is a common cause for rejection.
Sometimes, applicants might not fully understand the ‘severe and prolonged’ criteria. An impairment that causes discomfort but doesn’t significantly restrict a basic activity of daily living for at least 12 continuous months might not meet the CRA’s strict definition. It’s crucial for both the applicant and the medical professional to interpret these terms accurately. Misinterpreting these core requirements often leads to applications that do not align with the program’s intent.
Tips to Avoid Delays and Denials
Be Detailed: Provide as much specific information as possible about how the impairment affects daily life.
Communicate with Your Doctor: Discuss the DTC criteria with your medical practitioner before they complete Part B to ensure they understand what information is needed.
Gather Supporting Documents: While not always required initially, having medical reports, test results, or therapy schedules ready can be helpful if the CRA requests more information.
Review Carefully: Before submitting, double-check that all sections are complete, legible, and accurate.
Follow Up: If you haven’t heard back within the CRA’s stated processing times, follow up on your application status.
By being meticulous and proactive, you can significantly reduce the likelihood of your Disability Tax Credit application being delayed or denied. A well-prepared application saves everyone time and ensures you access your benefits sooner.
Appealing a Disability Tax Credit Decision
Receiving a denial for your Disability Tax Credit application can be disheartening, but it’s important to remember that it’s not always the final word. You have the right to appeal the CRA’s decision, and many successful applicants have gone through this process. The first step in appealing is to understand *why* your application was denied. The CRA will send you a letter explaining their decision, which usually points to specific reasons such as insufficient medical information or not meeting the ‘severe and prolonged’ criteria.
Once you understand the reason for denial, you can prepare your appeal. This often involves gathering additional medical evidence or obtaining a more detailed letter from your medical practitioner. Your doctor might need to provide more specific examples of how your impairment affects your daily activities, directly addressing the CRA’s stated reasons for denial. Sometimes, a different medical professional with a specialty more directly related to your condition might be able to offer a more compelling assessment.
You can formally object to the CRA’s decision by sending a letter or by using Form T400A, Objection – Income Tax Act. This objection must be filed within 90 days from the date on the notice of assessment or reassessment, or within one year from the due date of the return for the year in question. Clearly state that you are objecting to the DTC decision and provide all new or clarified information. Include any new medical reports, specialist opinions, or personal statements that strengthen your case. Be as thorough as possible.
If your objection is also denied, you still have further avenues. You can appeal to the Tax Court of Canada. While this step can be more complex and might involve legal representation, it is an option for those who strongly believe they meet the eligibility criteria and have exhausted other avenues. Throughout the entire appeal process, maintaining detailed records of all communication with the CRA and copies of all submitted documents is absolutely essential. Don’t give up if you believe you are genuinely eligible for the Disability Tax Credit; persistence can pay off.
Frequently Asked Questions
Q: How long does it take for the CRA to process a Disability Tax Credit application?
A: Processing times can vary, but generally, the CRA aims to process T2201 forms within a few weeks to a few months. It’s always best to check the current processing times on the CRA website, as they can fluctuate based on volume and complexity of the application.
Q: Can I apply for the DTC if my disability is not visible?
A: Absolutely. The Disability Tax Credit applies to both visible and invisible disabilities, as long as they meet the ‘severe and prolonged’ criteria and significantly restrict a basic activity of daily living. Mental health conditions, chronic pain, and neurological disorders are common examples of invisible disabilities that can qualify.
Q: What if my medical practitioner charges a fee to complete Form T2201?
A: Medical practitioners are permitted to charge a fee for completing forms like T2201, as this is not covered by provincial health insurance plans. This fee is considered a medical expense and may be eligible for the medical expense tax credit on your income tax return.
Q: Do I need to reapply for the Disability Tax Credit every year?
A: Not necessarily. The CRA will indicate on your approval letter how long your eligibility is valid. For permanent conditions, approval can last for many years. For conditions that may improve, you might be approved for a shorter period and would need to reapply when that period ends.
Q: Can a child qualify for the Disability Tax Credit?
A: Yes, children with severe and prolonged impairments can qualify for the DTC. The credit can then be claimed by a supporting parent or guardian, providing significant financial assistance to families caring for a child with a disability. The eligibility criteria remain the same as for adults.
The Disability Tax Credit represents a vital source of financial relief for many Canadians living with disabilities and their families. With an average of $2,500 in annual savings, and the potential for significant retroactive claims, understanding and accessing this credit can profoundly impact financial well-being. The application process, while requiring attention to detail, is manageable with the right information and guidance. By ensuring your Form T2201 is accurately and thoroughly completed by both yourself and your medical practitioner, you lay the groundwork for a successful application.
Beyond the immediate tax savings, the DTC opens doors to other beneficial programs like the Registered Disability Savings Plan, further enhancing long-term financial security. Don’t be deterred by potential delays or denials; armed with knowledge about common pitfalls and the appeals process, you can confidently navigate the system. We encourage all eligible individuals and their supporting family members to explore the Disability Tax Credit. It’s a fundamental support designed to alleviate some of the unique financial burdens associated with living with a severe and prolonged impairment, helping ensure a more stable and secure future.