First-Time Home Buyer Incentive: Access Up to 10% Down Payment
Discover the First-Time Home Buyer Incentive and how it can help you secure your dream home. This guide explains how to access up to 10% for your down payment, eligibility criteria, and the application process, making homeownership more accessible for Canadians.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
Exploring the First-Time Home Buyer Incentive: How to Access Up to 10% for Your Down Payment
Dreaming of owning your first home but struggling with the down payment? The First-Time Home Buyer Incentive could be the key to unlocking that dream. This government program aims to make homeownership more affordable for eligible Canadians by offering a shared-equity mortgage, potentially providing up to 10% of the home’s purchase price for your down payment.
Understanding how this incentive works and if you qualify is crucial for anyone looking to enter the housing market. It’s designed to reduce your monthly mortgage payments without increasing your financial burden, making that first home feel a lot closer. Let’s dive into the details of this valuable opportunity.
What is the First-Time Home Buyer Incentive?
The First-Time Home Buyer Incentive (FTHBI) is a program introduced by the Canadian government to help first-time homebuyers reduce their monthly mortgage payments. It does this by offering a shared-equity mortgage, meaning the government takes a percentage ownership in your home. This percentage is based on the amount of the incentive you receive.
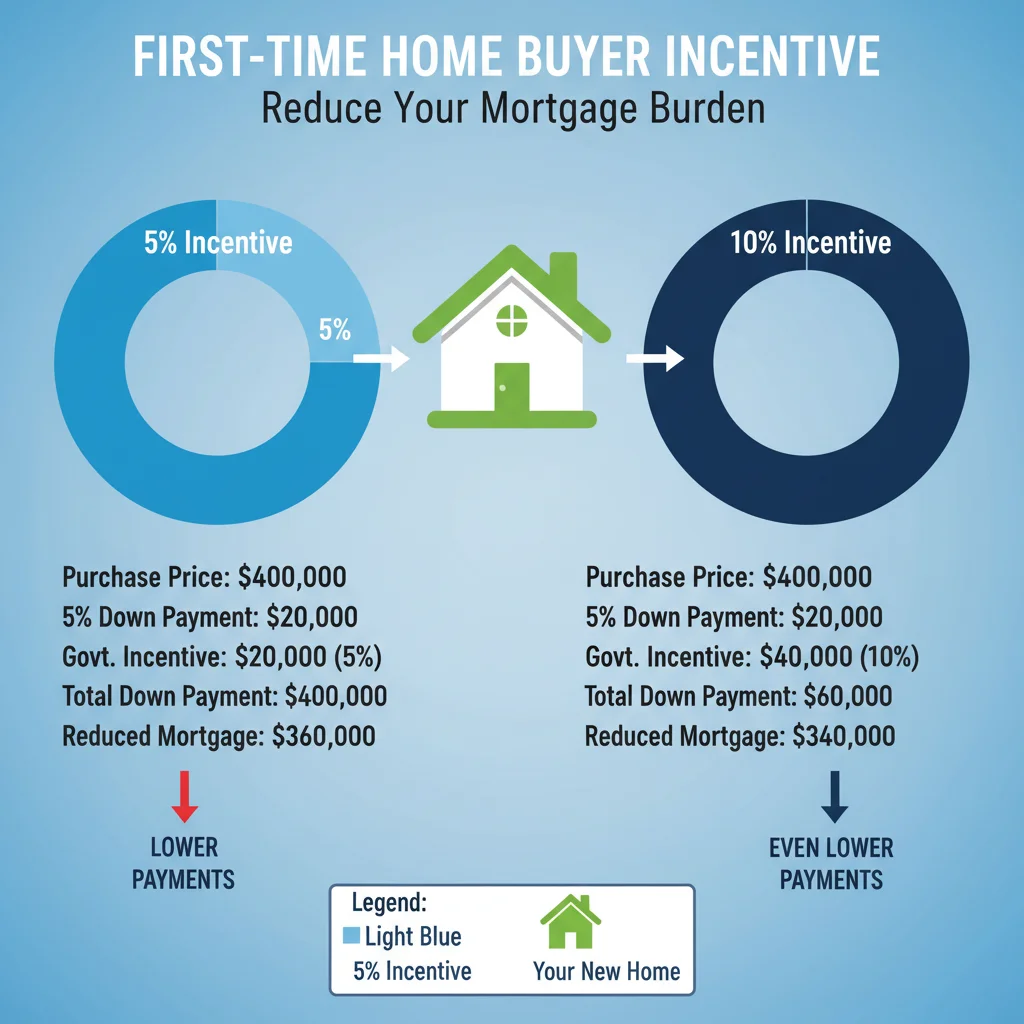
Essentially, the incentive acts as an interest-free loan that contributes to your down payment. For a newly constructed home, you could receive up to 10% of the purchase price, and for existing homes, up to 5%. This additional boost to your down payment helps lower the total amount you need to borrow from a traditional lender, which in turn reduces your mortgage principal and, consequently, your monthly payments. The program is administered by the Canada Mortgage and Housing Corporation (CMHC), ensuring it adheres to strict guidelines and is accessible to those who need it most.
The FTHBI is not a grant; it’s a second mortgage on your property. This means you will need to repay the incentive at some point. The repayment is based on the property’s fair market value at the time of repayment, not the original incentive amount. This shared-equity model means that if your home value increases, the amount you owe back to the government will also increase proportionally. Conversely, if your home’s value decreases, your repayment amount would also decrease.
Who Qualifies for the First-Time Home Buyer Incentive?
Qualifying for the First-Time Home Buyer Incentive involves meeting specific criteria designed to ensure the program helps those who need it most. The primary requirement is that you must be a first-time home buyer. This means you haven’t owned a home in the last four years, or you’ve experienced a breakdown of a marriage or common-law partnership, even if you previously owned a home. This flexibility helps individuals re-enter the housing market under challenging circumstances.
Beyond being a first-time buyer, there are income limitations. Your total annual qualifying income must not exceed $120,000. This income threshold is calculated based on the combined income of all applicants on the mortgage. This ensures the program targets individuals and families who genuinely require assistance to afford a home, rather than those who could likely purchase a home without government support. It’s a crucial aspect of the program’s fairness and effectiveness.
Another important factor is your total borrowing. Your insured mortgage and the incentive amount combined cannot be more than four times your total annual qualifying income. This limit helps prevent buyers from taking on too much debt, promoting responsible homeownership. For instance, if your household income is $100,000, your combined mortgage and incentive cannot exceed $400,000. This ensures that even with the incentive, your overall debt load remains manageable, reducing the risk of financial strain down the line. Understanding these financial boundaries is key to a successful application.
Key Eligibility Requirements
First-Time Home Buyer Status: You must meet the definition of a first-time home buyer, which generally means no home ownership in the last four years.
Income Threshold: Your total qualifying annual income cannot be more than $120,000.
Borrowing Limit: Your total insured mortgage and the incentive amount cannot exceed four times your qualifying income.
Minimum Down Payment: You must have the minimum required down payment (typically 5%) from your own resources.
Property Type: The property must be located in Canada and must be suitable for year-round occupancy.
Meeting all these requirements is essential for your application to be considered. It’s always a good idea to consult with a mortgage professional or financial advisor to confirm your eligibility before proceeding with an application.
How Much Can You Get and What Are the Repayment Terms?
The First-Time Home Buyer Incentive offers different levels of assistance depending on the type of home you are purchasing. For newly constructed homes, you can receive 5% or 10% of the home’s purchase price. This higher incentive for new builds is designed to stimulate housing supply and support the construction industry. For existing homes, the incentive is capped at 5% of the purchase price. This distinction is important as it influences the maximum amount of assistance you can receive and, consequently, how much your monthly mortgage payments might be reduced.
Understanding the repayment terms is crucial because the incentive is not a free grant. It’s a shared-equity mortgage, meaning the government shares in the appreciation or depreciation of your home’s value. You must repay the incentive after 25 years or when you sell the home, whichever comes first. The repayment amount is calculated based on the fair market value of your home at the time of repayment. For example, if you received a 10% incentive on a $400,000 home ($40,000), and the home’s value increases to $500,000, you would repay 10% of $500,000, which is $50,000. Conversely, if the home’s value decreased, your repayment amount would also decrease proportionally.
While the repayment can seem daunting, especially with potential home value increases, it’s important to remember the immediate benefit: lower monthly mortgage payments. This immediate relief can make homeownership more accessible and sustainable in the short term. The program allows for voluntary repayment at any time without penalty, which can be a strategic move if you anticipate significant home value appreciation or if your financial situation improves. Planning for this future repayment is a key part of leveraging the First-Time Home Buyer Incentive effectively.
Applying for the First-Time Home Buyer Incentive
Applying for the First-Time Home Buyer Incentive involves a few straightforward steps, typically integrated into your mortgage application process. The first step is to get pre-approved for a mortgage from a participating lender. This is usually a bank, credit union, or other financial institution that works with CMHC. During this pre-approval process, you’ll discuss your financial situation, income, and the type of home you’re looking to purchase. The lender will help you determine if you meet the FTHBI eligibility criteria, including the income and borrowing limits, before you even begin your home search.
Once you’ve found a home and have an accepted offer, your lender will submit your application for the incentive to CMHC on your behalf. This submission includes all the necessary documentation, such as proof of income, details of the property, and confirmation of your first-time home buyer status. It’s important to ensure all your documents are accurate and up-to-date to avoid any delays in the application process. CMHC then reviews the application to ensure it meets all program requirements. This review process usually takes a few business days.
Upon approval, the incentive amount will be provided at the time of your home’s closing and will be applied directly to your down payment. This seamless integration means you don’t have to manage a separate fund, simplifying the transaction. Working closely with your mortgage broker or lender throughout this process is crucial. They are familiar with the intricacies of the program and can guide you through each step, ensuring a smooth and successful application for the First-Time Home Buyer Incentive. Don’t hesitate to ask them any questions you have along the way.
Benefits and Considerations of the Incentive
The First-Time Home Buyer Incentive offers several compelling benefits, primarily making homeownership more attainable for many Canadians. The most significant advantage is the reduction in your monthly mortgage payments. By increasing your down payment with government assistance, you borrow less from your primary lender, leading to lower principal and interest payments each month. This can free up significant funds in your budget, making homeownership less financially stressful and more sustainable, especially for those new to the responsibilities of property ownership.
Another major benefit is the potential to enter the housing market sooner. For many, saving a substantial down payment is the biggest hurdle to buying a home. The FTHBI helps bridge this gap, allowing first-time buyers to purchase a home without waiting years to save the full amount. This can be particularly advantageous in rising real estate markets, where property values can increase significantly while you’re still saving. Getting into the market earlier can mean building equity sooner and benefiting from potential appreciation.
However, there are important considerations to weigh. The shared-equity model means the government shares in your home’s value appreciation. If your home’s value increases, you will repay more than the original incentive amount. This is a crucial aspect that prospective buyers must understand. While it provides immediate relief, it comes with a future financial obligation that grows with your property’s value. It’s essential to factor this into your long-term financial planning and consider how potential future repayment might impact your equity or future home sales.
Additionally, the program has specific income and borrowing limits, which might exclude some buyers, particularly in high-cost housing markets where property values exceed the program’s thresholds. It’s important to assess if the incentive truly aligns with your financial goals and the type of property you intend to purchase. Consulting with a financial advisor can help you understand all the implications and decide if the First-Time Home Buyer Incentive is the right path for your homeownership journey, ensuring you make an informed decision for your financial future.
Frequently Asked Questions
Is the First-Time Home Buyer Incentive a grant?
No, the First-Time Home Buyer Incentive is not a grant. It’s a shared-equity mortgage, meaning the government takes a percentage ownership in your home and expects repayment based on the home’s fair market value at the time of repayment or sale.
Can I repay the incentive early?
Yes, you can repay the incentive in full at any time without incurring a pre-payment penalty. This flexibility allows you to manage your finances strategically, especially if your home value has increased significantly.
What happens if my home’s value decreases?
If your home’s value decreases, the amount you owe back to the government for the incentive will also decrease proportionally. The repayment is always based on the fair market value at the time of repayment, not the original incentive amount.
Are there any regional restrictions for the incentive?
The First-Time Home Buyer Incentive is available across Canada, but specific regions may have varying market conditions that impact the program’s practical applicability due to property price caps and income limits. It’s important to check the specific limits for your desired location.
Do I need to pay interest on the incentive?
No, the First-Time Home Buyer Incentive is an interest-free loan. You only repay the principal amount, adjusted for the home’s appreciation or depreciation, without any added interest charges.
The First-Time Home Buyer Incentive stands as a significant opportunity for many Canadians looking to step into homeownership. By offering a shared-equity mortgage, the program effectively reduces the initial financial hurdle of a down payment, leading to more manageable monthly mortgage payments. This initiative not only helps individuals and families realize their dream of owning a home sooner but also contributes to a more stable and accessible housing market across the country.
While the prospect of repaying a larger sum if your home appreciates might seem like a drawback, the immediate benefits of reduced financial strain and accelerated entry into the market are often invaluable. It’s a strategic tool that, when understood and utilized correctly, can provide a crucial boost to your homeownership journey. Remember to thoroughly assess your eligibility, understand the repayment structure, and consult with financial experts to ensure this incentive aligns perfectly with your long-term financial goals. Taking these steps will empower you to make an informed decision and confidently pursue your first home.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.