CEBA Repayment Deadline: What Canadian Businesses Must Know
The CEBA repayment deadline is fast approaching for Canadian businesses. This article outlines everything you need to know about the Canada Emergency Business Account, including repayment terms, eligibility for partial loan forgiveness, and critical dates to ensure your business makes informed decisions and avoids financial penalties.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
The Canada Emergency Business Account (CEBA) program played a vital role in supporting countless Canadian small businesses during the economic challenges brought on by the pandemic. Now, a crucial CEBA repayment deadline looms, and understanding its implications is paramount for the nearly 500,000 businesses that received these loans. Missing this deadline could mean forfeiting a significant portion of the loan that was initially offered as forgivable.
As December 31st rapidly approaches, business owners must grasp the specific repayment terms, potential extensions, and the steps required to maximize their loan forgiveness. This article will delve into the essential details, helping you navigate the complexities of the CEBA program and ensure your business is well-prepared for the upcoming financial obligations.
Understanding the CEBA Program and Its Origins
The Canada Emergency Business Account (CEBA) was a cornerstone of the Canadian government’s response to the economic fallout from the COVID-19 pandemic. Launched in April 2020, its primary goal was to provide interest-free loans to small businesses and non-profit organizations, helping them cover operating costs during a period of unprecedented uncertainty. Many businesses faced sudden closures or drastic reductions in revenue, and CEBA offered a lifeline to keep them afloat, pay employees, and manage essential expenses like rent and utilities. The program quickly became one of the most widely utilized support initiatives, demonstrating the immense need for financial assistance across the country.
Initially, the program offered loans of up to $40,000, which was later expanded to $60,000 for eligible businesses. A key feature that made CEBA so attractive was the promise of partial loan forgiveness. If businesses repaid a certain portion of their loan by a specific deadline, the remaining balance would be forgiven. This incentive was designed to encourage responsible repayment while still providing substantial relief. The initial design aimed to support businesses through the immediate crisis, allowing them to focus on survival and recovery without the added burden of full loan repayment.
The eligibility criteria for CEBA were broad, encompassing a wide range of small businesses and non-profits, provided they met certain payroll or non-deferrable expense thresholds. This broad reach ensured that a significant portion of the Canadian business landscape could access the much-needed funds. The government’s intention was clear: to inject liquidity into the economy and prevent widespread business failures, thereby preserving jobs and maintaining economic stability during a turbulent period. As the pandemic evolved, so too did the CEBA program’s terms, particularly regarding repayment timelines, which brings us to the present critical juncture for businesses.
The Critical CEBA Repayment Deadline: What You Need to Know
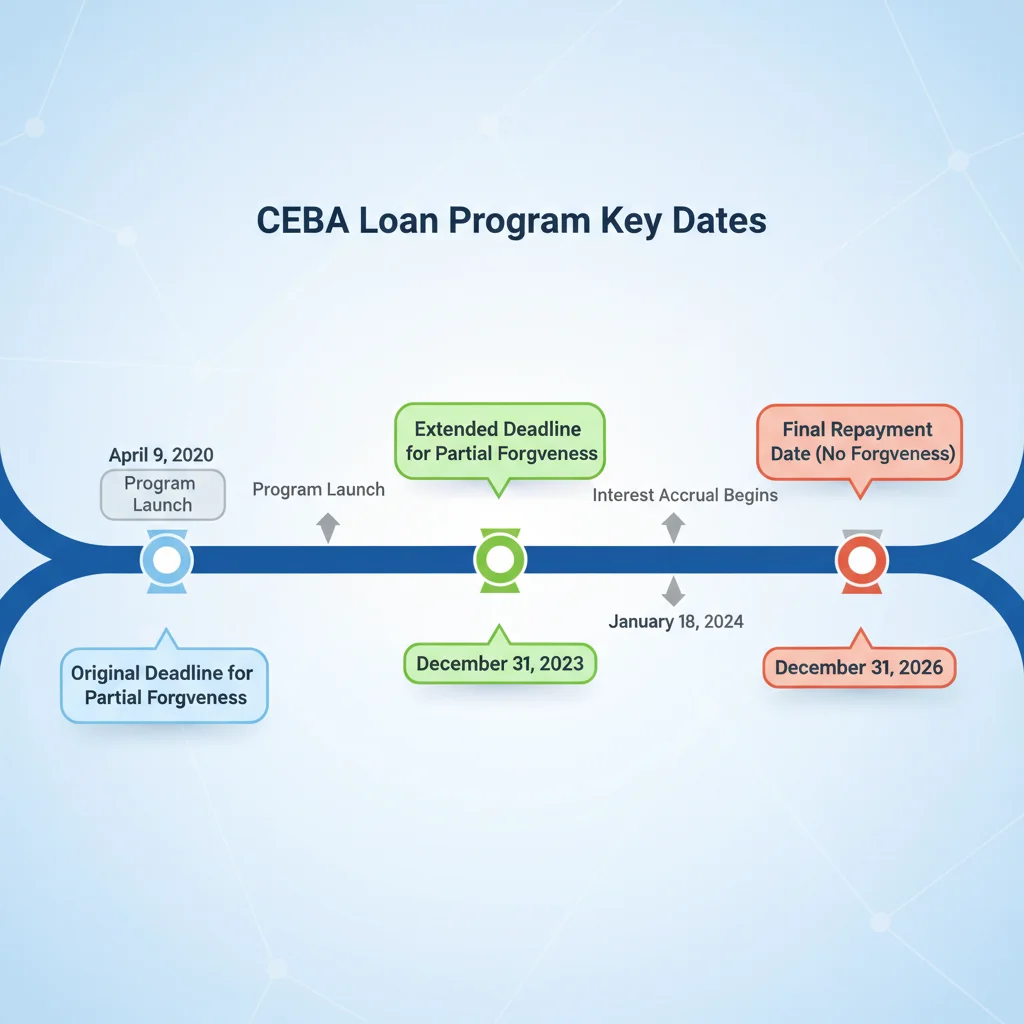
The most pressing concern for businesses that received CEBA loans is the impending repayment deadline. Originally set for December 31, 2022, the government extended this crucial date to provide businesses with more time to recover and prepare for repayment. The new primary deadline to qualify for partial loan forgiveness is now **January 18, 2024**. This extension was a welcome relief for many, acknowledging the ongoing economic challenges and the time needed for businesses to regain their footing.
Meeting this January 18, 2024, deadline is essential because it directly impacts the amount of loan forgiveness your business can receive. For loans of $60,000, if you repay $40,000 by this date, the remaining $20,000 will be forgiven. Similarly, for the original $40,000 loans, repaying $30,000 by the deadline results in $10,000 being forgiven. This non-repayable portion represents a significant benefit that businesses should strive to secure. Failing to meet this deadline means the entire loan amount will convert to a two-year term loan with interest, starting January 19, 2024, at an annual interest rate of 5%.
It’s important to differentiate between the various repayment scenarios. If you do not repay the eligible amount by January 18, 2024, your loan will automatically transition to a standard term loan. This means you will lose the opportunity for partial forgiveness, and you will be obligated to repay the full amount plus interest by December 31, 2026. This shift from a potentially forgivable, interest-free loan to an interest-bearing debt underscores the urgency of understanding and acting upon the CEBA repayment deadline. Businesses should actively engage with their financial institutions to confirm their specific loan amount and repayment requirements to avoid any surprises.
Strategies for Meeting Your Repayment Obligations
Preparing for the CEBA repayment deadline requires careful planning and a clear understanding of your business’s financial position. The first step is to accurately assess your current cash flow and determine how much capital you can realistically allocate towards the repayment. Review your balance sheets and income statements to identify any potential shortfalls or opportunities for generating additional revenue. This comprehensive financial review will help you form a solid repayment strategy and prevent last-minute stress.
Many businesses may find themselves in a position where they need external financing to meet the partial forgiveness deadline. Several options are available, and exploring them early is crucial. Traditional bank loans, lines of credit, or even government-backed small business loans could provide the necessary funds. It’s advisable to speak with your financial institution or a financial advisor to discuss the best fit for your specific circumstances. They can help you understand interest rates, repayment schedules, and application processes for alternative financing.
Exploring Repayment Options
Re-financing with Your Primary Financial Institution: Many banks that originally issued CEBA loans are offering specific refinancing options to help businesses meet the forgiveness deadline. These might include new term loans or lines of credit tailored to cover the CEBA balance.
Government-Backed Loan Programs: Investigate other federal or provincial loan programs designed to support small businesses. While not directly tied to CEBA, they could provide capital to free up funds for your CEBA repayment.
Personal Savings or Investments: For some business owners, leveraging personal funds might be a viable, albeit significant, option to secure the loan forgiveness. Carefully weigh the pros and cons of this approach with a financial advisor.
Accelerated Revenue Generation: Implement short-term strategies to boost sales or reduce expenses. This could involve special promotions, optimizing inventory, or negotiating better terms with suppliers to free up cash.
Regardless of the strategy chosen, early action is key. Procrastination could lead to missed opportunities for favorable financing or, worse, missing the January 18, 2024, deadline entirely, thereby losing the valuable partial forgiveness. Start discussions with your bank and financial advisors today to chart the most effective path forward for your business.
Impact of Missing the CEBA Repayment Deadline
Missing the CEBA repayment deadline of January 18, 2024, has significant financial consequences for businesses. The most immediate and impactful outcome is the forfeiture of the partial loan forgiveness. As mentioned, for a $60,000 loan, this means losing the opportunity to have $20,000 written off. For a $40,000 loan, it’s a $10,000 loss. This amount then becomes part of the total principal that must be repaid, significantly increasing the overall debt burden on the business. This alone can strain cash flow and hinder future growth plans, especially for businesses still in recovery mode.
Furthermore, any outstanding CEBA loan balance not repaid by January 18, 2024, will automatically convert into a two-year term loan. This new loan will carry an annual interest rate of 5%, applied from January 19, 2024, until the final repayment date of December 31, 2026. While a 5% interest rate might seem manageable, it adds up over time, especially on a larger principal. Businesses that were accustomed to an interest-free loan will suddenly face monthly interest payments, which can impact profitability and operational budgets. This shift requires a complete re-evaluation of financial projections and cash flow management.
Beyond the direct financial costs, missing the deadline can also have broader implications for a business’s financial health and future borrowing capacity. Increased debt levels and interest payments can negatively affect a company’s creditworthiness, making it harder to secure future loans or lines of credit at favorable terms. Lenders often look at a business’s debt-to-equity ratio and its ability to service existing debt when evaluating new applications. A higher debt burden from an un-forgiven CEBA loan could be a red flag. Therefore, understanding these potential ramifications is crucial for making an informed decision about how to approach the CEBA repayment deadline.
Preparing for the Final Repayment and Future Steps
Even if a business misses the January 18, 2024, deadline for partial loan forgiveness, the obligation to repay the full loan amount plus interest remains. The final repayment date for all CEBA loans, including those that converted to interest-bearing term loans, is December 31, 2026. This provides businesses with a two-year window to settle their full debt. During this period, interest will accrue at 5% annually, making it imperative to establish a clear repayment plan to avoid further financial strain. Businesses should consider setting up regular, structured payments to chip away at the principal and interest.
To effectively manage this ongoing debt, businesses should integrate the CEBA loan repayments into their long-term financial planning. This involves updating budgets, forecasting cash flow, and potentially adjusting business operations to ensure sufficient funds are available. Working with an accountant or financial advisor can be highly beneficial in creating a realistic and sustainable repayment schedule. They can help analyze your financial statements, identify areas for cost reduction or revenue enhancement, and explore strategies to minimize the overall interest paid over the two-year term.
Beyond the immediate repayment, businesses should also reflect on the lessons learned from the CEBA experience and the pandemic. Strengthening financial resilience, building emergency funds, and diversifying revenue streams are all valuable practices that can help safeguard against future economic shocks. The CEBA program served its purpose in a crisis, but moving forward, proactive financial management will be key to long-term stability and growth. Ensuring all financial records related to the CEBA loan are meticulously maintained will also be important for any future audits or financial reviews. The final CEBA repayment deadline of December 31, 2026, marks the true closure of this chapter for Canadian businesses.
Frequently Asked Questions
What is the new CEBA repayment deadline for partial loan forgiveness?
The new deadline to repay your CEBA loan and qualify for partial forgiveness is January 18, 2024. Originally, it was December 31, 2022, but was extended to give businesses more time.
How much loan forgiveness can I receive?
For a $60,000 CEBA loan, repaying $40,000 by the deadline results in $20,000 forgiveness. For a $40,000 loan, repaying $30,000 by the deadline leads to $10,000 forgiveness.
What happens if I miss the January 18, 2024, deadline?
If you miss this deadline, your entire CEBA loan amount will convert into a two-year term loan with a 5% annual interest rate, effective January 19, 2024, due by December 31, 2026.
Can I still get an extension if I need more time?
While the primary forgiveness deadline is January 18, 2024, businesses that have applied for a refinancing loan from the financial institution that provided their CEBA loan may be eligible for an extension until March 28, 2024, to obtain partial forgiveness.
Where can I find my CEBA loan balance and specific terms?
You should contact the financial institution (your bank or credit union) that originally issued your CEBA loan. They can provide your exact loan balance, repayment terms, and details on how to make your payment.
The approaching CEBA repayment deadline on January 18, 2024, represents a pivotal moment for hundreds of thousands of Canadian businesses. Understanding the nuances of this program, particularly the opportunity for partial loan forgiveness, is not just a recommendation but a necessity for financial stability. Businesses that act proactively to repay the eligible portion of their loan by this date stand to save a significant amount, converting what could be a substantial debt into a manageable, partially forgiven sum. Failure to meet this deadline will result in the entire loan becoming interest-bearing, adding an unexpected financial burden for the next two years.
It is crucial for every CEBA loan recipient to confirm their specific repayment obligations with their financial institution, explore all available refinancing options, and develop a robust repayment strategy. Whether through internal cash flow, external financing, or a combination of approaches, timely action is paramount. The government’s extensions have offered valuable breathing room, but the finality of the upcoming deadline demands immediate attention. By taking informed steps now, Canadian businesses can successfully navigate this final phase of the CEBA program, safeguard their financial future, and continue on their path to recovery and growth.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.