Canada’s Digital Services Tax: What Businesses Need to Know
Canada is implementing a new Digital Services Tax (DST) starting April 1, impacting businesses with significant digital revenue. This post explores the implications, who is affected, and crucial steps for compliance, ensuring your business is prepared for these regulatory changes.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
Canada’s New Digital Services Tax: Implications for Businesses Starting April 1
Canada is set to introduce a significant change to its tax landscape with the implementation of a new Canada digital tax, officially known as the Digital Services Tax (DST), starting April 1. This new tax aims to ensure that large multinational corporations generating revenue from Canadian users of digital services contribute their fair share to the Canadian economy. The move aligns Canada with a global trend of countries seeking to tax the digital economy more effectively, reflecting the evolving nature of commerce in the 21st century.
For many businesses, especially those operating in the digital realm, understanding the specifics of this new tax is paramount. It’s not just about knowing that a new tax exists; it’s about comprehending its scope, identifying whether your business falls within its purview, and preparing for the operational and financial adjustments that will inevitably follow. This article will delve into the critical aspects of Canada’s Digital Services Tax, offering insights into its potential impact and guiding businesses through the necessary steps for compliance.
Understanding the Scope and Rationale Behind the DST
The Canadian government’s decision to implement the Digital Services Tax stems from a broader international effort to address the challenges of taxing highly digitalized businesses. Traditional tax rules often struggle to capture the value created by companies that operate across borders with minimal physical presence. These companies frequently generate substantial revenue from users in various jurisdictions, yet their profits are often taxed in countries where their intellectual property or headquarters are located, rather than where the value is generated.
Canada’s DST is designed to capture a portion of the revenue generated from certain digital services consumed by Canadian users. This includes revenue from online marketplaces, social media, search engines, and the sale of user data. The rationale is fairness and ensuring that all businesses, regardless of their physical footprint, contribute equitably to public services in the places where they earn their money. While international discussions on a multilateral solution continue, Canada has moved forward with its own domestic measure to address this perceived gap in taxation. This proactive approach underscores Canada’s commitment to adapting its tax framework to the modern digital economy, even as global consensus remains elusive.
It’s important to recognize that this tax is not a universal levy on all digital transactions. Instead, it specifically targets large enterprises that meet certain revenue thresholds, both globally and within Canada. This selective application is intended to focus the tax burden on companies with significant economic activity in the digital space, rather than smaller businesses or startups. The government has emphasized that the DST is a temporary measure, intended to be replaced once a satisfactory international agreement on digital taxation is reached. However, for now, businesses must prepare for its immediate implications and integrate it into their financial planning.
Who Will Be Affected by the New Canada Digital Tax?
The new Canada Digital Services Tax is not a broad-brush tax that will impact every business operating online. Instead, it is specifically designed to target large multinational enterprises that generate substantial revenue from digital activities involving Canadian users. Understanding the thresholds and criteria for applicability is crucial for businesses to assess their potential exposure. The Canadian government has outlined clear guidelines to determine which entities fall under the scope of this new tax regime.
Primarily, the DST applies to groups of companies that have annual global revenues of at least 750 million euros (approximately C$1.1 billion) and, more specifically, generate at least C$20 million in Canadian digital services revenue within a calendar year. This dual threshold ensures that only the largest and most globally integrated digital service providers are subject to the tax. Smaller businesses, startups, and those with limited digital revenue from Canadian users are generally exempt. The tax applies to revenue derived from specific categories of digital services, including online marketplaces facilitating interactions between users, social media platforms, search engines, and the sale or licensing of user data for advertising purposes. It’s not about taxing every online sale, but rather specific digital business models that leverage user engagement and data.
Businesses engaged in these activities, and meeting the revenue thresholds, will need to carefully track their Canadian-sourced digital services revenue. This involves robust data collection and reporting mechanisms to accurately determine their tax liability. Companies that might be affected include major tech giants, e-commerce platforms, and advertising technology firms. Even if a company does not have a physical presence in Canada, if it meets the revenue thresholds and generates revenue from Canadian users through the specified digital services, it will likely be subject to the DST. This extraterritorial reach is a defining characteristic of digital services taxes globally, and it presents unique compliance challenges for international businesses.
Key Digital Services Covered Under the DST
The Canada Digital Services Tax specifically targets certain categories of digital services, reflecting where the Canadian government believes significant value is being generated from Canadian users. It’s not a blanket tax on all online commercial activities, but rather a focused approach on particular digital business models. Understanding these categories is essential for businesses to accurately assess their obligations and ensure compliance with the new regulations coming into effect.
Specific Digital Service Categories:
Online Marketplaces: This category includes digital platforms that facilitate interactions and transactions between users, such as e-commerce sites where third-party sellers offer goods or services to Canadian buyers. Revenue derived from commissions, listing fees, or advertising on these platforms, when related to Canadian users, would typically be subject to the DST.
Social Media Services: Platforms that enable users to interact with each other, share content, and build networks are also covered. Revenue generated from advertising displayed to Canadian users on these platforms, or from premium features purchased by Canadian users, falls under this scope.
Search Engine Services: Revenue from search engine services that are used by Canadian individuals or businesses is included. This primarily targets advertising revenue linked to search results and other related services provided to Canadian users.
Sale or Licensing of User Data: This is a crucial component, targeting revenue derived from the monetization of data collected from Canadian users. If a business collects data from Canadian users and then sells or licenses that data for advertising or other commercial purposes, the revenue generated from such activities would be subject to the DST.
It’s important to note that certain digital services are explicitly excluded from the DST. For instance, traditional telecommunication services, financial services, and educational services provided digitally are generally not subject to this tax. The focus remains on services that primarily derive their value from user engagement and data monetization in the digital sphere. Businesses must carefully review their revenue streams against these defined categories to determine which portions are relevant for DST calculation. The complexity arises from the need to accurately attribute revenue to Canadian users, which often requires sophisticated data analytics and internal tracking systems to ensure precise reporting and avoid potential penalties.
Preparing for Compliance: Steps Businesses Should Take
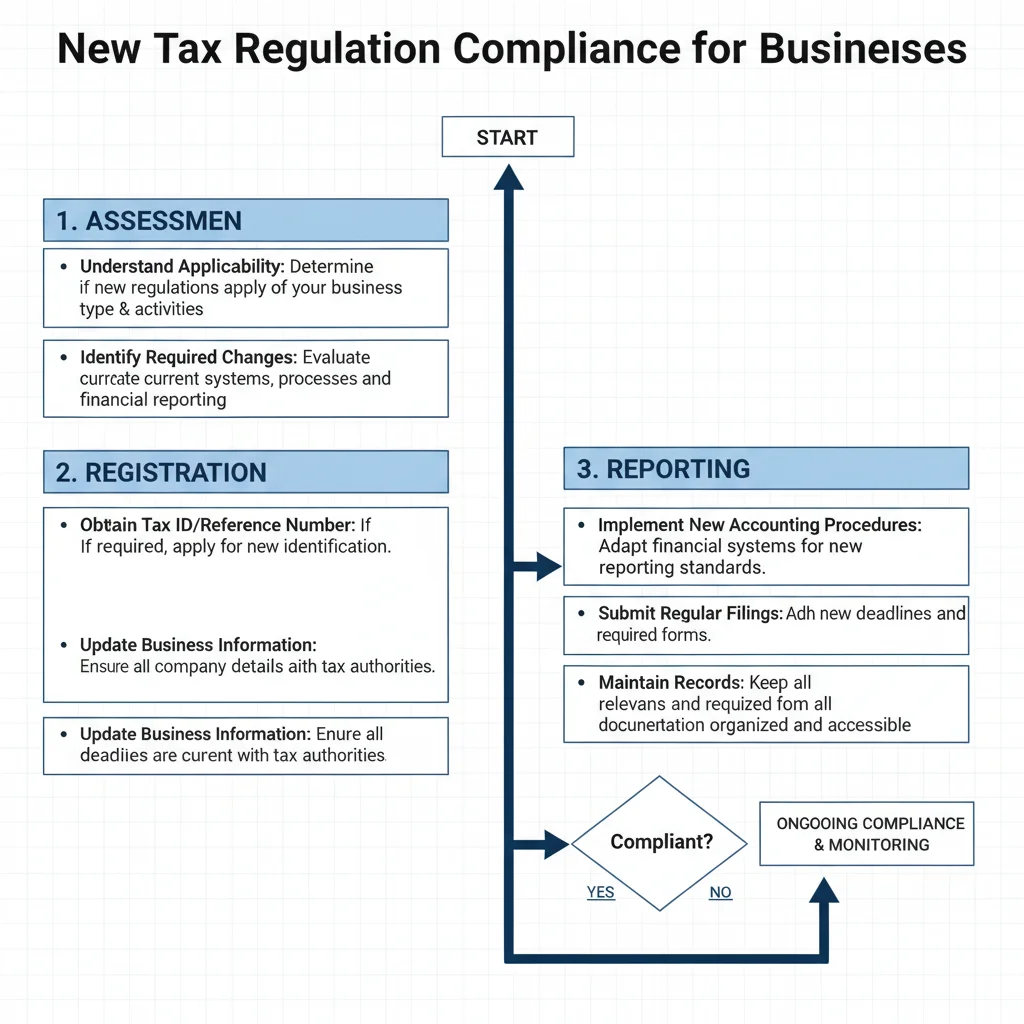
As the April 1 implementation date for the Canada Digital Services Tax approaches, businesses that anticipate being affected must proactively prepare for compliance. This isn’t merely about understanding the tax; it’s about integrating new processes, updating systems, and potentially adjusting business strategies to meet the regulatory requirements. Early and thorough preparation can help mitigate risks, ensure accurate reporting, and avoid penalties associated with non-compliance. The steps involved can be complex, requiring cross-departmental collaboration and expert advice.
The first critical step is to conduct a thorough internal assessment of your digital revenue streams. This involves identifying all services provided to Canadian users that fall under the specified categories of online marketplaces, social media, search engines, and data monetization. Businesses need to meticulously track revenue generated from these services, ensuring they can differentiate Canadian-sourced revenue from global revenue. This often requires robust data analytics capabilities and potentially new accounting classifications to segregate relevant income. Understanding your exact Canadian digital services revenue against the C$20 million threshold is fundamental.
Once the assessment is complete, businesses should focus on updating their accounting and reporting systems. This might involve implementing new software modules or adapting existing systems to capture and report DST-relevant data accurately. It’s also advisable to consult with tax professionals specializing in Canadian tax law and digital taxation. They can provide tailored advice, help interpret complex regulations, and ensure your compliance strategy is sound. Furthermore, businesses should establish internal controls and processes for ongoing monitoring and reporting. This includes designating responsible personnel, setting up review mechanisms, and staying informed about any future guidance or amendments to the DST legislation. Proactive engagement with these steps will position businesses to navigate the new tax landscape effectively and maintain good standing with Canadian tax authorities.
Potential Impact and Future Outlook of the DST
The introduction of the Canada Digital Services Tax is poised to have several significant impacts, not only on the multinational corporations directly subject to it but also on the broader digital economy and potentially on Canadian consumers. Understanding these potential ramifications is crucial for businesses as they navigate this new regulatory environment. The effects could range from changes in pricing strategies to shifts in investment decisions, influencing how digital services are offered and consumed in Canada.
For the affected multinational corporations, the most immediate impact will be an additional tax burden, which could reduce their profit margins from Canadian operations. How these companies respond could vary. Some might absorb the cost, viewing it as a necessary expense for operating in the Canadian market. Others might choose to pass a portion of the cost onto Canadian consumers through increased prices for digital services, advertising rates, or subscription fees. This could potentially lead to higher costs for businesses that rely on digital advertising and for individuals using various online platforms. The competitive landscape could also shift, as companies re-evaluate their presence or investment levels in the Canadian market based on the profitability of their digital services.
Looking to the future, the DST is explicitly stated by the Canadian government as a temporary measure. Canada has indicated that it intends to remove the DST once a multilateral solution for taxing the digital economy is adopted at an international level, such as through the OECD’s Pillar One initiative. However, the timeline for such an international agreement remains uncertain. In the interim, the DST provides Canada with a mechanism to collect revenue from large digital businesses. The ongoing discussions at the OECD aim to create a more harmonized and stable global tax framework for the digital economy, which would ultimately replace fragmented national approaches like Canada’s DST. Businesses should stay abreast of these international developments, as a global consensus would likely trigger further adjustments to Canada’s tax policy, potentially leading to the repeal or modification of the current DST framework.
Frequently Asked Questions
What is the Canada Digital Services Tax (DST)?
The Canada Digital Services Tax (DST) is a new tax on revenue generated from certain digital services provided to Canadian users by large multinational enterprises. It aims to ensure these companies contribute their fair share to the Canadian economy, addressing challenges in taxing the digital economy.
When does the Canada Digital Services Tax come into effect?
The Canada Digital Services Tax is scheduled to come into effect on April 1. Businesses falling under its scope will need to begin tracking and reporting relevant revenue from this date onwards.
Which businesses are subject to the DST?
The DST applies to multinational groups with annual global revenues of at least 750 million euros (approx. C$1.1 billion) and Canadian digital services revenue of C$20 million or more in a calendar year.
What types of digital services are covered by the DST?
The DST covers revenue from online marketplaces, social media services, search engine services, and the sale or licensing of user data, specifically when these services are provided to Canadian users.
Is the Canada Digital Services Tax a permanent measure?
No, the Canadian government has stated that the DST is a temporary measure. It is intended to be replaced once a satisfactory international agreement on taxing the digital economy is adopted, such as through the OECD’s Pillar One initiative.
The impending implementation of Canada’s Digital Services Tax on April 1 marks a pivotal moment for businesses operating in the digital sphere. This new tax represents Canada’s proactive step towards adapting its fiscal policies to the realities of the modern digital economy, ensuring that large multinational corporations contribute equitably to the national tax base. For affected businesses, understanding the nuances of the DST – from its scope and revenue thresholds to the specific digital services it targets – is no longer optional but a critical imperative.
Preparation for compliance requires a multi-faceted approach, encompassing thorough revenue assessments, system adjustments, and potentially strategic re-evaluations. While the DST is presented as a temporary measure, contingent on international consensus, its immediate impact on operational costs and market dynamics in Canada is undeniable. Businesses must engage with tax professionals, establish robust internal tracking mechanisms, and stay informed about both domestic regulatory updates and global discussions on digital taxation. By taking these proactive steps, companies can navigate the complexities of this new tax landscape effectively, ensuring continued compliance and minimizing potential disruptions to their Canadian operations. The era of the Canada digital tax is here, and preparedness is key to success.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.