Maximize Your TFSA: $7,000 Contribution Limit for Growth
Discover how to fully leverage your TFSA contribution limit for optimal financial growth. This guide breaks down the $7,000 annual limit, explains contribution room, and offers strategies for maximizing your tax-free investment potential in Canada.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
Understanding and fully utilizing your TFSA contribution limit is a cornerstone of smart financial planning in Canada. The Tax-Free Savings Account (TFSA) offers an incredible opportunity for Canadians to grow their wealth without paying taxes on investment income, interest, or capital gains. With the annual TFSA contribution limit set at $7,000 for 2024, it’s more important than ever to grasp how this powerful tool works to maximize your financial future.
Many Canadians are still not taking full advantage of their TFSA’s potential, often leaving valuable contribution room on the table. This guide will walk you through the specifics of the TFSA, explain how to calculate your personal contribution room, and provide actionable strategies to ensure you’re making the most of every dollar. We’ll delve into various investment options suitable for a TFSA and highlight common pitfalls to avoid, helping you build a robust, tax-efficient portfolio.
By the end of this article, you’ll have a clear roadmap to navigate your TFSA contributions, understand the benefits of tax-free growth, and feel confident in making informed decisions about your savings. Let’s unlock the full potential of your TFSA together, transforming your financial goals into reality with strategic planning and consistent action.
Understanding Your TFSA Contribution Room
One of the most crucial aspects of maximizing your TFSA is fully understanding how your contribution room is calculated. The Canada Revenue Agency (CRA) sets an annual TFSA dollar limit, which for 2024 is $7,000. However, your personal contribution room isn’t just this year’s limit. It’s a cumulative amount that includes all unused contribution room from previous years, starting from when you turned 18 (or 2009, whichever is later). Any withdrawals you make from your TFSA in a given year are also added back to your contribution room at the beginning of the following year, making it a truly flexible savings vehicle.
For instance, if you were 18 or older in 2009 and have never contributed to a TFSA before, your total cumulative contribution room would be significantly higher than the annual $7,000. This accumulated room can be a substantial sum, offering a large capacity for tax-free investments. It’s essential to keep accurate records of your contributions and withdrawals to avoid over-contributing, which can lead to penalties. The CRA provides a service where you can check your available TFSA contribution room through your online account, which is always the most reliable source for this information.
Many people find tracking their TFSA room a bit confusing, especially with withdrawals and re-contributions. The key takeaway is that unused room carries forward indefinitely, and withdrawals replenish your room in the subsequent year. This design encourages long-term saving while providing liquidity when needed. Knowing your exact TFSA contribution limit prevents costly mistakes and ensures you’re always optimizing your tax-free growth potential. Make it a habit to check your CRA account annually before making significant contributions.
Strategic Investment Choices Within Your TFSA
Once you understand your available TFSA contribution limit, the next step is to choose the right investments to hold within it. A TFSA is not an investment itself, but rather a special type of account that *holds* investments. This means you can choose from a wide range of investment products, and the growth from these investments will be completely tax-free. The best investment choices for your TFSA depend on your financial goals, risk tolerance, and investment horizon. For those seeking steady growth with moderate risk, a diversified portfolio of exchange-traded funds (ETFs) or mutual funds can be an excellent option, offering exposure to various markets and asset classes.
If you have a higher risk tolerance and a longer time horizon, individual stocks can offer significant growth potential within a TFSA. The capital gains from selling profitable stocks are entirely tax-free, which can lead to substantial savings compared to holding them in a taxable account. Conversely, for those who are more risk-averse or nearing retirement, guaranteed investment certificates (GICs) or high-interest savings accounts (HISAs) held within a TFSA can provide predictable, tax-free returns. These options offer stability and capital preservation, ensuring your savings are secure while still benefiting from the tax-free status.
It’s also worth considering dividend-paying stocks or equity income funds within your TFSA. The dividends earned from these investments are tax-free, which can significantly boost your overall returns, especially over the long term. Reinvesting these tax-free dividends can supercharge the compounding effect, leading to accelerated wealth accumulation. Always remember to align your investment choices with your personal financial plan and consult with a financial advisor if you need personalized guidance. The flexibility of the TFSA allows you to tailor your investment strategy to perfectly suit your needs.
Maximizing Your Annual $7,000 Contribution
With the 2024 TFSA contribution limit at $7,000, making the most of this annual allocation is key to optimizing your tax-free growth. For many, contributing the full amount at the beginning of the year is the most effective strategy. This allows your investments more time in the market, potentially benefiting from an entire year of tax-free growth and compounding. If you have the funds available, a lump-sum contribution on January 1st can kickstart your annual savings journey with maximum efficiency. This approach is particularly beneficial for those investing in assets with strong growth potential, as it maximizes the period over which those gains can accumulate tax-free.
However, not everyone has $7,000 readily available at the start of the year. In such cases, a dollar-cost averaging strategy can be highly effective. This involves contributing smaller, regular amounts throughout the year, such as $583.33 each month. This method helps to mitigate the risk of investing a large sum at an market peak, as your average purchase price is smoothed out over time. It also promotes a disciplined savings habit, ensuring you consistently contribute towards your TFSA goal without feeling overwhelmed by a single large deposit. Whether you choose a lump sum or regular contributions, the crucial point is to contribute as much as you can, as early as you can, up to your TFSA contribution limit.
Another often-overlooked strategy is to prioritize your TFSA over other taxable investment accounts, especially if you have limited funds. Given the tax-free nature of all growth within a TFSA, it generally offers a superior return compared to a non-registered account, assuming similar investments. If you have both registered retirement savings plans (RRSPs) and TFSAs, consider your current and future income levels when deciding which to prioritize. For those in a lower tax bracket now but expecting higher income later, the TFSA can be an excellent choice. Always aim to fully exhaust your TFSA contribution room before considering taxable investment vehicles.
Avoiding Common TFSA Pitfalls and Penalties
While the TFSA offers incredible benefits, there are several common pitfalls that Canadians should be aware of to avoid unnecessary penalties and ensure their tax-free growth remains intact. The most significant mistake is over-contributing to your TFSA. If you contribute more than your available TFSA contribution room, the CRA will impose a penalty tax of 1% per month on the highest excess amount. This penalty can quickly erode your tax-free gains and is entirely avoidable with proper record-keeping and by regularly checking your contribution room through your CRA My Account.
Understanding Contribution Rules
Over-contribution: Exceeding your available room incurs a 1% monthly penalty on the excess.
Re-contribution timing: Withdrawals replenish your room, but only in the *next* calendar year. Re-contributing in the same year as a withdrawal can lead to over-contribution if you don’t have existing room.
Ineligible investments: Holding certain investments, like those in private corporations you own, can be deemed non-qualified and lead to penalties. Stick to publicly traded securities or common investment products.
Day trading: While not strictly prohibited, engaging in excessive day trading within a TFSA can lead the CRA to classify your activities as a business, making your gains taxable.
Foreign withholding tax: Be aware that while Canadian dividends are tax-free in a TFSA, foreign dividends may be subject to a non-recoverable withholding tax by the source country. This doesn’t impact your TFSA’s tax-free status with the CRA, but it does reduce your net return.
Another common misunderstanding relates to withdrawals and re-contributions. If you withdraw funds from your TFSA, that amount is added back to your contribution room, but only at the beginning of the *next* calendar year. If you re-contribute the withdrawn amount in the same year, and you don’t have sufficient existing contribution room, you could inadvertently over-contribute. Always plan your withdrawals and re-contributions carefully to stay within your limits. By being diligent and understanding these rules, you can ensure your TFSA remains a powerful tool for tax-free wealth accumulation.
Long-Term Growth Strategies for Your TFSA
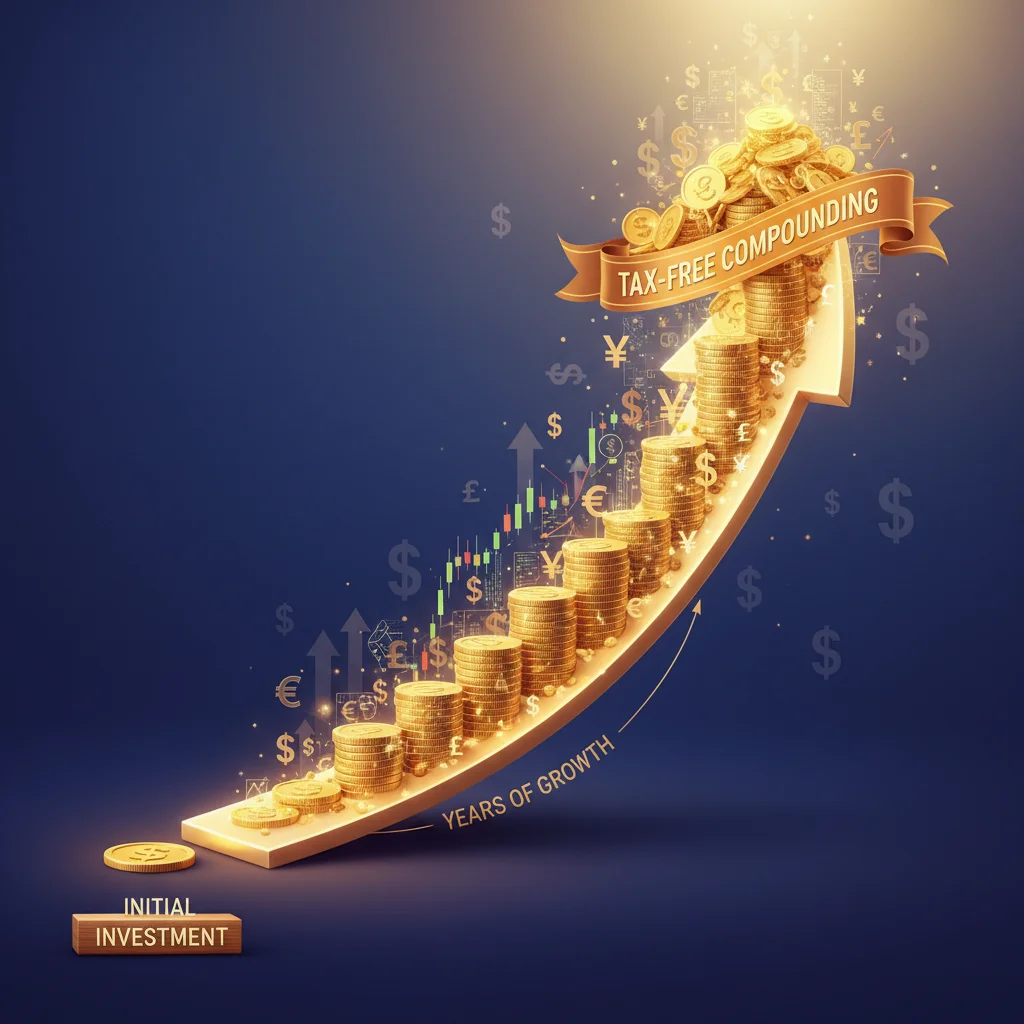
The true power of the TFSA is realized over the long term, thanks to the magic of compounding interest and tax-free growth. Developing a long-term strategy for your TFSA is paramount to maximizing its potential. This involves not just consistently contributing up to your TFSA contribution limit each year, but also making thoughtful investment choices that align with your long-term financial objectives. For many, a buy-and-hold strategy within a TFSA proves to be incredibly effective. By investing in quality assets and allowing them to grow over decades, you can benefit significantly from compounding without the drag of annual taxes on your gains.
Consider structuring your TFSA portfolio with a long-term perspective. This might mean investing in growth-oriented equities, low-cost index funds, or ETFs that track broad market indices. These investments are designed to appreciate over extended periods, and holding them within a TFSA means every dollar of profit is yours to keep, tax-free. Rebalancing your portfolio periodically, perhaps once a year, helps ensure your asset allocation remains consistent with your risk tolerance and financial goals. This disciplined approach prevents your portfolio from drifting too far from your intended strategy due to market fluctuations.
Another powerful long-term strategy is to think of your TFSA as a supplement to your retirement savings, working in tandem with your RRSP. While RRSPs offer an immediate tax deduction, TFSAs provide tax-free withdrawals in retirement, which can be invaluable for income planning. By maximizing both accounts, you create a diversified tax strategy for your golden years. The flexibility of TFSA withdrawals also makes it an excellent account for saving for other major life goals, such as a down payment on a house or a child’s education, as you can access your funds without tax implications. Consistent contributions and a well-thought-out investment plan are the cornerstones of long-term TFSA success.
Frequently Asked Questions
What is the maximum TFSA contribution limit for 2024?
The maximum TFSA contribution limit for 2024 is $7,000. This amount is set by the Canada Revenue Agency (CRA) and is subject to change each year based on inflation.
How can I find out my exact TFSA contribution room?
The most accurate way to find your exact TFSA contribution room is to log in to your CRA My Account online. The CRA tracks your contributions and withdrawals and will display your personalized room.
Can I lose money in a TFSA?
Yes, you can lose money in a TFSA. While the account itself is tax-free, the investments held within it are subject to market fluctuations. If your investments perform poorly, their value can decrease.
What happens if I over-contribute to my TFSA?
If you over-contribute to your TFSA, the CRA will charge a penalty tax of 1% per month on the highest excess amount. It’s crucial to withdraw the excess funds as soon as you realize the mistake to minimize penalties.
Can I have more than one TFSA?
Yes, you can have multiple TFSA accounts with different financial institutions. However, the total amount you contribute across all your TFSA accounts cannot exceed your personal TFSA contribution limit.
Harnessing the full potential of your TFSA is a powerful step towards achieving your financial aspirations. By diligently understanding your TFSA contribution limit, consistently contributing the annual $7,000, and making informed investment choices, you can build substantial wealth that grows completely tax-free. The flexibility of the TFSA, combined with the magic of compounding, makes it an indispensable tool for both short-term savings goals and long-term retirement planning.
Remember to regularly check your available contribution room with the CRA to avoid any penalties and to strategically plan your withdrawals and re-contributions. Whether you opt for a lump-sum deposit or regular contributions, the key is to stay disciplined and keep your investments aligned with your personal financial objectives. Don’t let this incredible opportunity pass you by. Take action today to maximize your TFSA, secure your financial future, and enjoy the benefits of tax-free growth for years to come.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.