TFSA Contribution Limits: Navigating the $7,000 Increase
Explore the historical growth of TFSA contribution limits and prepare for the potential $7,000 increase. Learn how to strategically use your TFSA to boost your tax-free savings and achieve your financial goals in Canada.
By: pedropadm2025@gmail.com on August 22, 2026
Última atualização em: agosto 24, 2026
The Tax-Free Savings Account (TFSA) has become a cornerstone of financial planning for many Canadians. Since its introduction, the TFSA contribution limits have steadily evolved, offering individuals a powerful tool to save and invest without paying taxes on their gains. Understanding these limits, especially the anticipated $7,000 increase, is crucial for maximizing your tax-free growth potential and achieving your long-term financial goals.
This article will guide you through the history of TFSA contribution limits, explain how the new increase impacts your financial strategy, and provide practical tips for making the most of this valuable savings vehicle. Whether you’re a seasoned investor or just starting, grasping the nuances of your TFSA is key to building a secure financial future.
The Genesis and Growth of TFSA Contribution Limits
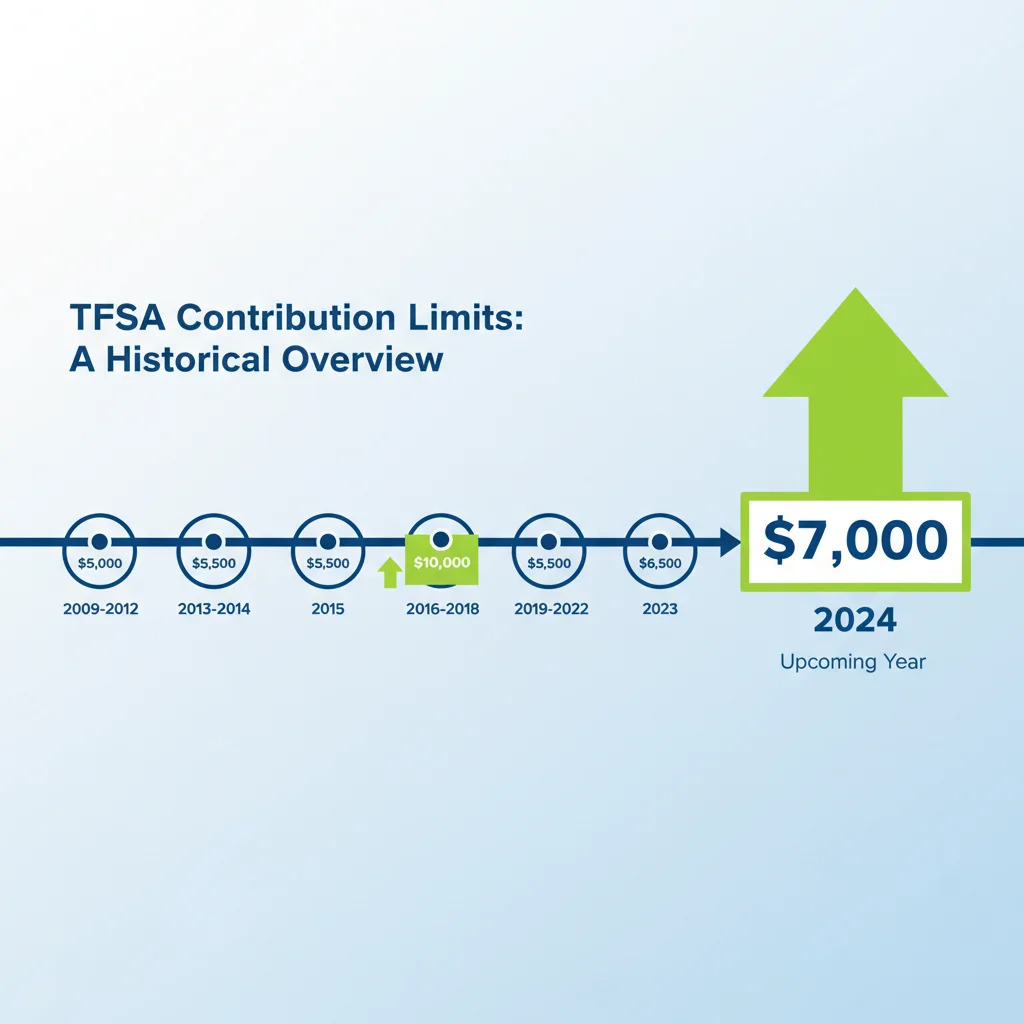
The Tax-Free Savings Account was first introduced in 2009, revolutionizing the way Canadians save. Its initial annual contribution limit was set at $5,000, a significant sum that allowed individuals to begin building a substantial tax-free nest egg. The concept was simple yet brilliant: any investment income, capital gains, or dividends earned within a TFSA are completely tax-free, even when withdrawn. This immediate benefit made the TFSA an instant success, providing a flexible alternative or complement to registered retirement savings plans (RRSPs).
Over the years, the government has adjusted the TFSA contribution limits to account for inflation and economic changes, ensuring the account remains relevant and impactful for savers. These adjustments are tied to the Consumer Price Index (CPI), rounded to the nearest $500, which provides a predictable, albeit not always annual, increase. This mechanism helps maintain the purchasing power of your tax-free savings over time. The steady growth in these limits reflects the government’s commitment to encouraging personal savings and financial independence among its citizens.
For example, after its debut at $5,000, the limit saw increases to $5,500 and even a temporary jump to $10,000 in one particular year before reverting. These changes underscore the dynamic nature of the TFSA and the importance of staying informed about the latest adjustments to fully leverage its benefits. Each increase presents a new opportunity to grow your wealth more efficiently, free from the burden of taxation.
Understanding the $7,000 TFSA Contribution Limit
The anticipation of the TFSA contribution limits reaching $7,000 marks another significant milestone for Canadian savers. This increase, driven by the indexation to inflation, provides an enhanced opportunity for individuals to save more money without incurring taxes on their investment returns. It’s a clear signal that the TFSA remains a vital component of Canada’s financial landscape, designed to help ordinary Canadians accumulate wealth more effectively. For those who consistently maximize their contributions, this additional $500 per year can lead to substantial gains over the long term, especially when compounded.
This new limit means that if you have never contributed to a TFSA before, your total cumulative contribution room will jump significantly, allowing you to deposit a much larger sum tax-free. For instance, someone who turned 18 in 2009 and has never contributed would have accumulated a considerable amount of room, which the $7,000 addition further expands. It’s essential to remember that unused contribution room carries forward indefinitely, making the TFSA an incredibly flexible savings vehicle even if you can’t contribute the maximum every year.
Keeping track of your personal contribution room is crucial to avoid over-contributing, which can result in penalties. The Canada Revenue Agency (CRA) provides access to your TFSA contribution room through My Account, ensuring you have accurate information at your fingertips. Regularly checking this resource will help you plan your contributions strategically and take full advantage of the new $7,000 limit without any missteps. This proactive approach ensures you maximize your tax-free growth potential.
Strategic Planning with the Increased TFSA Limits
With the TFSA contribution limits rising to $7,000, it’s an opportune moment to re-evaluate your financial strategy and ensure you’re making the most of this powerful savings tool. Strategic planning is key to maximizing the benefits of your TFSA, whether your goal is saving for a down payment, retirement, or simply building an emergency fund. The increased room allows for greater flexibility in allocating your savings, potentially accelerating your progress towards various financial milestones.
Optimizing Your Contributions
Prioritize maxing out: Aim to contribute the full $7,000 each year if your financial situation allows. This ensures you’re leveraging the maximum tax-free growth opportunity available to you.
Consider a lump sum: If possible, contributing a lump sum at the beginning of the year allows your investments more time to grow tax-free, benefiting from longer compounding periods.
Automate your savings: Set up automatic transfers from your chequing account to your TFSA. Even small, regular contributions can add up over time and help you reach the annual limit without feeling a pinch.
Reinvest dividends: If your TFSA holds dividend-paying stocks or funds, consider reinvesting those dividends back into the account. This compounds your returns even faster, all within the tax-free environment.
Beyond simply contributing, think about the types of investments you hold within your TFSA. Growth-oriented investments, such as stocks or equity-focused exchange-traded funds (ETFs), can particularly benefit from the tax-free environment, as their capital gains won’t be taxed. Conversely, fixed-income investments like GICs or bonds, while safer, might not fully exploit the tax-free growth potential as much as higher-growth assets. Your investment choices should align with your risk tolerance and financial goals, but the TFSA provides an excellent wrapper for diverse asset classes.
Comparing TFSA to Other Savings Vehicles
Understanding how the TFSA contribution limits compare to other common savings vehicles, such as Registered Retirement Savings Plans (RRSPs) and non-registered accounts, is essential for a holistic financial plan. Each account type serves a distinct purpose and offers unique benefits, making the choice dependent on your individual financial situation and goals. The TFSA stands out for its unmatched flexibility and tax-free withdrawals, which is a significant advantage many other accounts do not offer.
RRSPs, for instance, offer immediate tax deductions on contributions, reducing your taxable income in the year you contribute. However, withdrawals from an RRSP are fully taxable in retirement. This makes RRSPs ideal for individuals who expect to be in a lower tax bracket in retirement than during their working years. The TFSA, on the other hand, offers no upfront tax deduction, but all withdrawals are completely tax-free, regardless of your income level in retirement. This makes the TFSA particularly attractive for those who anticipate a similar or higher tax bracket in retirement, or for those who need access to their funds before retirement without tax implications.
Non-registered accounts, while offering unlimited contribution room, do not provide any tax advantages. All investment income, capital gains, and dividends earned in these accounts are subject to annual taxation. This means a significant portion of your returns can be eroded by taxes over time, making them less efficient for long-term growth compared to TFSAs or RRSPs. Therefore, once you’ve maximized your TFSA and RRSP contributions, non-registered accounts become the next logical step for additional savings, but they should generally be prioritized after utilizing your tax-advantaged options. The flexibility of the TFSA, especially with its increasing limits, truly sets it apart as a versatile tool for various financial objectives.
Maximizing Your TFSA: Practical Tips and Best Practices
To truly maximize the benefits of your TFSA, especially with the anticipated $7,000 contribution limit, it’s important to adopt a few practical tips and best practices. These strategies go beyond simply contributing and focus on optimizing your investment choices, managing your withdrawals, and staying informed. By implementing these approaches, you can ensure your TFSA works as hard as possible for you, helping you achieve your financial aspirations faster and more efficiently.
One key best practice is to understand the implications of withdrawals. While TFSA withdrawals are tax-free, the contribution room they free up is only reinstated the following calendar year. This means if you withdraw funds in the current year, you cannot re-contribute those funds until January 1st of the next year without potentially over-contributing. Planning your withdrawals carefully, especially for large expenses, can prevent accidental over-contributions and ensure you always have the maximum possible room available. For example, if you know you’ll need a significant sum for a down payment next year, withdrawing it in December rather than January could allow you to re-contribute it sooner.
Another crucial tip is to choose investments wisely within your TFSA. Given that all gains are tax-free, it often makes sense to hold investments with higher growth potential or those that generate significant income, such as dividend stocks or real estate investment trusts (REITs), within your TFSA. These types of investments would typically be heavily taxed in a non-registered account, but inside a TFSA, their returns are completely sheltered. Conversely, lower-growth investments like high-interest savings accounts or GICs might be better suited for non-registered accounts if you’ve already maximized your TFSA and RRSP, as their smaller taxable gains will have less impact. Regularly reviewing and rebalancing your TFSA portfolio to align with your risk tolerance and financial goals is also a smart move, ensuring your assets are always working optimally for your tax-free growth.
Frequently Asked Questions
What is the primary benefit of a TFSA?
The primary benefit of a TFSA is that all investment income, including capital gains and dividends, earned within the account is completely tax-free, even when withdrawn. This allows your money to grow significantly faster compared to taxable accounts.
How do I find my current TFSA contribution room?
You can find your current TFSA contribution room by logging into your My Account on the Canada Revenue Agency (CRA) website. This provides the most accurate and up-to-date information on your available room.
Can I hold any type of investment in a TFSA?
Most common investments, such as stocks, mutual funds, exchange-traded funds (ETFs), guaranteed investment certificates (GICs), and bonds, can be held within a TFSA. However, certain investments, like real estate directly, are not permitted.
What happens if I over-contribute to my TFSA?
If you over-contribute to your TFSA, you will be charged a penalty tax of 1% per month on the highest excess amount for each month the excess remains in your account. It’s crucial to withdraw any excess contributions immediately.
Is the TFSA contribution limit cumulative?
Yes, the TFSA contribution limit is cumulative. If you don’t use all your contribution room in a given year, it carries forward indefinitely, allowing you to contribute the unused amount in future years.
The evolution of TFSA contribution limits, culminating in the anticipated $7,000 increase, underscores the account’s enduring importance for Canadian financial planning. From its inception in 2009, the TFSA has provided an unparalleled opportunity for individuals to grow their savings and investments without the burden of taxation. Understanding these changes, and particularly the impact of the new limit, is crucial for anyone looking to optimize their financial future.
By strategically utilizing the increased contribution room, whether through consistent contributions, wise investment choices, or careful planning of withdrawals, you can significantly accelerate your progress towards your financial goals. The TFSA offers flexibility that complements other savings vehicles like RRSPs, making it a versatile tool for everything from short-term savings to long-term retirement planning. Stay informed about your contribution room and make proactive decisions to truly maximize the benefits of this powerful tax-free account. Start planning today to fully leverage the advantages of the TFSA and secure your financial well-being.
pedropadm2025@gmail.com
Peter B holds a degree in Journalism and has 5 years of experience covering U.S. economic policy, labor markets, and financial news. He writes data-driven news content on topics like inflation, interest rates, and employment trends.